Categories
Uncategorized

Top 6 Lenders for HVAC AC Financing Options in 2026

Hvac ac financing

Top 6 Lenders for HVAC AC Financing Options in 2026

Last updated: 2026-10-16

When summer heat waves hit or winter chill seeps through the floorboards, a broken HVAC system feels like a sudden emergency. Most homeowners do not have several thousand dollars sitting in a drawer ready to cover a brand-new condenser unit or a furnace replacement. Specialized financing steps in to bridge the gap between a broken unit and a comfortable home.

Choosing the right way to pay for these essential repairs requires looking beyond just the monthly payment. You have to weigh the speed of funding against the long-term cost of interest and the potential impact on your credit score. This list examines various providers to help you find a path that fits your immediate budget and your long-term financial health.

  1. Hearth
  2. JetzLoan
  3. Flexxbuy
  4. AmeriCash Loans
  5. Roadrunner Financial
  6. NetCredit

The Standards for Evaluating HVAC Financing Providers

Finding a lender for home climate control is not like shopping for a car or a small personal loan. HVAC projects are often urgent. If your furnace dies in January, you cannot afford to wait two weeks for a bank to review your paperwork and verify your income.

The comparison below focuses on how quickly funds become available and what kind of credit profile is required to get through the door. Some lenders focus on high-ticket installment loans. Others specialize in quick, short-term advances or lease-to-own models for those with limited credit history. The goal is to match the lender’s strengths to the specific urgency of the repair.

Lender Name Max Loan Amount Funding Speed Credit Requirements
Hearth see site see site see site
JetzLoan $35,000 As little as 24 hours No hard credit pull
Flexxbuy $100,000 Next business day Credit Select (35+ lenders)
AmeriCash Loans see site Instant decision Good credit not needed
Roadrunner Financial see site Two minutes All credit welcome
NetCredit $10,000 Same-day funding available Flexible terms

1. Hearth

Hearth – hearth.com

Hearth operates as a specialized resource for those looking to optimize their home energy efficiency. While many lenders focus purely on the money, this platform provides a deep well of information regarding wood stoves, pellet stoves, and various energy-saving equipment. It acts as a community hub for those wanting to make responsible, clean, and safe fuel choices.

This is an ideal choice for the homeowner who wants to do their homework before committing to a major installation. Instead of just looking at a loan, you can dive into forums and discussions to understand the long-term benefits of the equipment you are financing. It is a knowledge-first approach to home improvement.

Pros:

  • Extensive community forums for technical advice.
  • Focus on energy-efficient and sustainable equipment.
  • Valuable historical data on various heating fuels.

Cons:

  • More of an information and advice resource than a direct lender.

2. JetzLoan
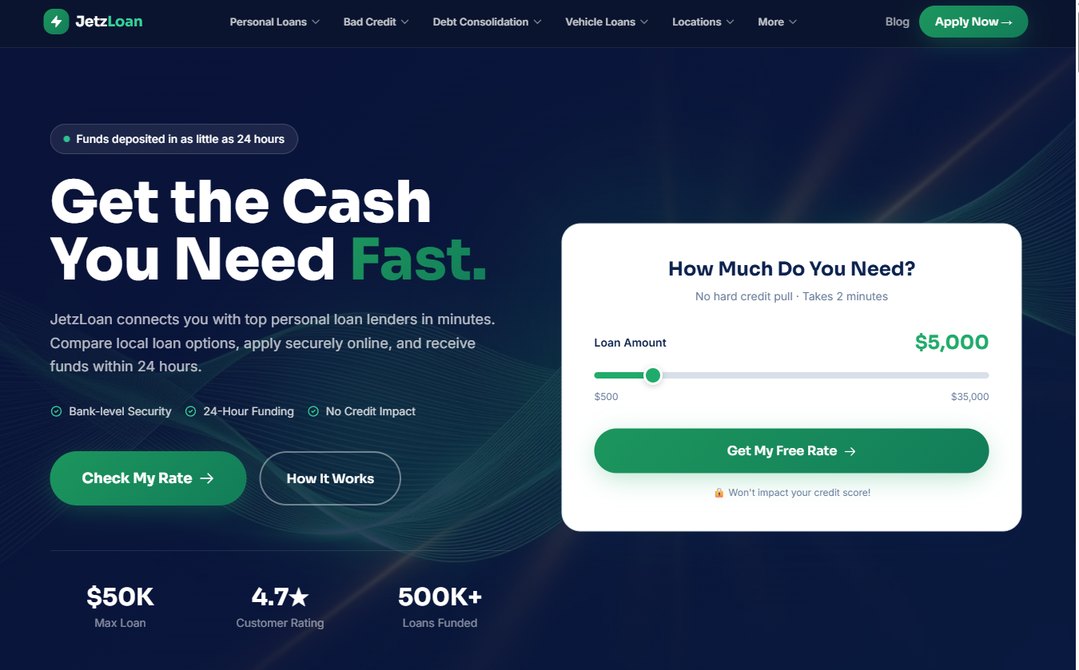
JetzLoan – jetzloan.com

Time is of the essence when your living room feels like a sauna. JetzLoan is built for the person who needs cash in their bank account yesterday. They focus on speed and simplicity, connecting users with top lenders in just a few minutes without the dread of a hard credit pull during the initial phase.

The process is streamlined to prevent the headache of endless paperwork. With the ability to receive funds in as little as 24 hours, it serves as a high-speed bridge for those facing sudden equipment failures. It is a straightforward solution for those who prioritize velocity over complex financial maneuvering.

Pros:

  • No hard credit pull during the initial rate check.
  • Extremely fast funding, potentially within 24 hours.
  • High maximum loan amount of up to $35,000.

Cons:

  • The speed of funding may depend on the specific lender matched.

3. Flexxbuy
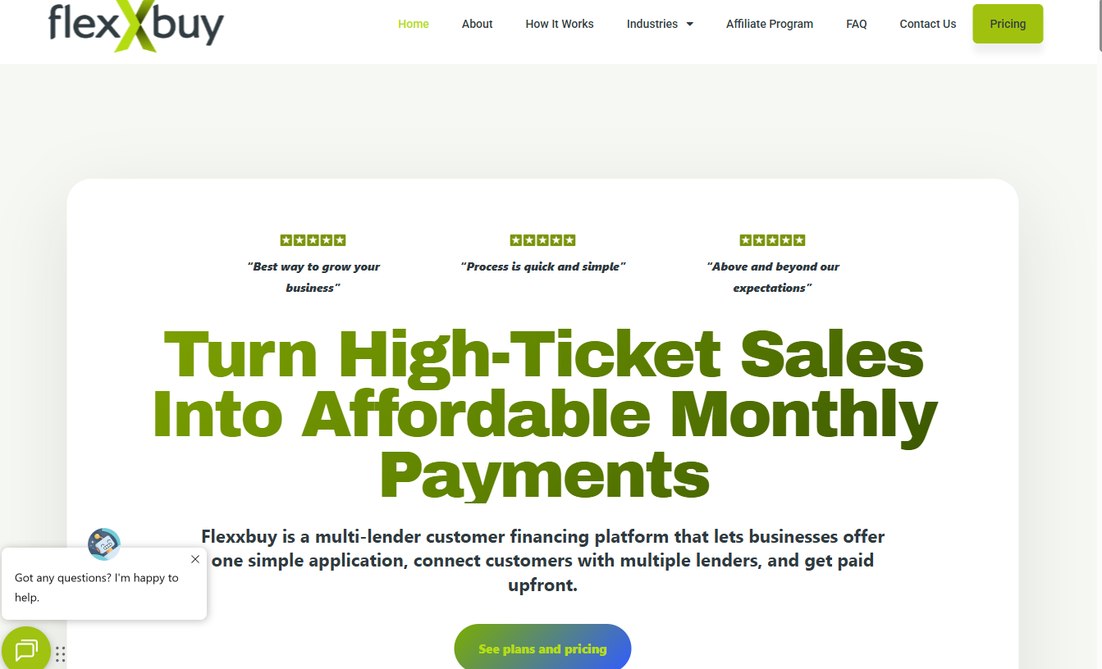
Flexxbuy – flexxbuy.com

For businesses and contractors installing expensive high-ticket HVAC systems, Flexxbuy offers a sophisticated way to close sales. They act as a multi-lender platform that allows customers to see several options through a single application. This turns a massive, intimidating price tag into manageable monthly installments that are much easier to swallow.

It is a powerful tool for scaling a business by making it easier for customers to say yes to premium equipment. With loan amounts reaching up to $100,000, it handles the heavy lifting for major commercial or residential installations. The speed of decision-making is designed to keep the project moving forward without delay.

Pros:

  • High loan limits up to $100,000.
  • Decisions are made in seconds.
  • Access to a wide network of over 35 lenders.

Cons:

  • Primarily designed for businesses to offer to their customers.

4. AmeriCash Loans
AmeriCash Loans – americash.com

Sometimes, the traditional banking route is a closed door. AmeriCash Loans is designed for those who need momentum immediately and might not qualify for standard bank loans. They specialize in short-term cash advances and marketplace lending, making it easier for people to find a lender that fits their specific situation.

The application is built to be simple and secure, moving through a marketplace to find a match. It is a fallback option for those who need to act now but may have a less-than-perfect credit history. While it is a marketplace rather than a single lender, it provides a path to quick decisions.

Pros:

  • Instant approval decisions are possible.
  • Good credit is not a strict requirement.
  • Simple, user-friendly application process.

Cons:

  • Terms and requirements are determined by individual lenders in the marketplace.

5. Roadrunner Financial
Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial offers a highly specialized approach to financing, often focusing on various types of vehicle and recreational equipment. However, their “all credit welcome” philosophy makes them a versatile option for those looking for quick, personalized loan offers. They aim to remove the haggling and hassle typically found at the point of sale.

The prequalification process is incredibly fast, taking only about two minutes. This allows you to see what you might qualify for without any commitment or impact on your credit score. It is a low-pressure way to gauge your options before you commit to a major purchase or repair.

Pros:

  • No impact on credit score during prequalification.
  • Very fast, two-minute process.
  • Welcomes all credit scores.

Cons:

  • The service is heavily geared toward specific vehicle/recreational types.

6. NetCredit
NetCredit – netcredit.com

NetCredit positions itself as a modern alternative to traditional banking, operating under the philosophy that you are more than just a number in a database. They offer personal loans and lines of credit that provide a level of flexibility that many rigid banks simply cannot match. It is a human-centric approach to digital lending.

If you need a loan up to $10,000 to get your AC running again, NetCredit provides a path with the potential for same-day funding. Their use of advanced algorithms allows for a more nuanced view of your ability to repay, which can be a lifesaver for those who fall just outside the standard FICO requirements.

Pros:

  • Potential for same-day funding.
  • Flexible terms and loan amounts up to $10,000.
  • A more nuanced approach to credit assessment.

Cons:

  • Loan availability is subject to state-specific regulations and partnerships.

Navigating Your Financing Options

When you are staring at a broken air conditioner in the middle of a heatwave, it is easy to make a rushed decision. Avoid the mistake of signing a lease-to-own agreement without understanding if you would be better off with a traditional loan. While lease-to-own can be easier to get, it is often much more expensive over the life of the agreement.

Always ask for a total cost of ownership breakdown. A low monthly payment might look attractive on the surface, but if the term is 96 months, you could end up paying for the unit three times over. Compare the interest rates across multiple providers and always check for any hidden fees that might sneak into the contract at the last minute.

Another common pitfall is failing to verify the credentials of the contractor alongside the lender. A great financing deal is wasted if the technician installing the unit is not licensed or insured. Ensure that the financing is tied to a reputable professional who provides a clear, written estimate before you sign any loan documents.
Categories
Uncategorized

The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026

Bad credit loans pennsylvania

The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026

Last updated: 2026-10-16

Life rarely gives you a heads-up when things go wrong. One minute you are driving through Allentown on a rainy Tuesday, and the next, your transmission gives out completely. Maybe an unexpected ER visit leaves you staring at a medical bill you didn’t see coming, or a sudden Pennsylvania winter sends your heating costs through the roof. These hiccups are stressful enough, but they become a nightmare when a low credit score stands between you and the cash you need to keep the lights on.

When past late payments or high credit card balances have bruised your FICO score, traditional banks often shut their doors. They act more like gatekeepers than helpers, leaving many residents to hunt for alternative lifelines. This is where subprime lending enters the picture, and it requires a sharp eye. You have to be careful, because the goal is to find a solution that doesn’t create a whole new crisis next month.

When you are looking for quick cash, your priorities usually shift. You might stop worrying about finding the absolute lowest interest rate and start focusing simply on finding a lender willing to say yes to your financial history. It is a survival tactic, certainly, but it demands a strategic approach to stay ahead of the curve.

  1. GadCapital
  2. FastLendGo
  3. Credit Human
  4. GreendayOnline
  5. Loanz
  6. OppLoans

Evaluating Lending Options Across the Keystone State

Finding a decent lender in Pennsylvania means looking past the flashy social media ads or the bright neon signs in busy city streets. You need to know how they handle credit checks, how fast the money actually hits your bank account, and what the loan amounts look like when you are in a pinch. A resident in Erie likely has different needs than someone living in Philadelphia.

A commuter might just need a quick loan for an auto repair to get to work. On the other hand, a small business owner might need a bridge loan to cover payroll until the next big contract clears. This ranking looks at the specific needs of people facing these kinds of emergencies. We looked at how quickly funds arrive and whether they offer installment-based options.

Avoiding the debt trap is the real goal. A payday loan that requires full repayment in just fourteen days can easily turn into a cycle of endless renewals. Installment loans are often a better bet because they offer a predictable repayment schedule that fits much better with a standard monthly paycheck. It is the difference between a temporary fix and a long-term struggle.

Lender Name Loan Amounts Credit Requirements Funding Speed
GadCapital $100 – $5000+ No Credit Check Instant/Same Day
FastLendGo $500 – $5000+ Bad Credit Welcome Quick Access
Credit Human From $500 No Credit Review See Site
GreendayOnline $100 – $5000 No Hard Credit Check Same Day
Loanz $100 – $10000 See Site Quick/Convenient
OppLoans See Site Does not affect FICO Same-Day Funding

1. GadCapital

GadCapital – gadcapital.com

GadCapital acts as a direct lifeline for people facing immediate financial trouble. They offer options that don’t require a traditional credit check, which is perfect for a Pittsburgh resident who needs cash right now to pay an overdue rent bill or an urgent utility charge. Their model moves much faster than the slow, bureaucratic verification processes at big national banks.

The platform handles everything from small $100 advances to larger sums over $5000. This flexibility matters. A $100 loan might cover a tank of gas and a few groceries, while a $5000 loan could fix a major emergency repair. It is a specialized choice for those who need to bypass the long scrutiny of conventional banks and need an instant digital response.

Pros:
  • No credit checks required for many options
  • High maximum loan amounts up to $5000+
  • Fast, instant online application process
Cons:
  • High urgency can lead to expensive terms

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a versatile partner for various personal financing needs. They don’t just look at one type of borrower, either. They offer solutions for auto repairs, dental bills, and even roof repairs. This variety makes them a useful starting point for anyone unsure which specific product will fit their situation. (fastlendgo.com)

Whether you need a $500 boost to get to your next paycheck or a $5000 personal loan to consolidate high-interest debts, they aim to make comparing local options simple. This is a great fit for people facing specific household emergencies, like an HVAC unit failing during a humid Pennsylvania summer.

Pros:
  • Wide variety of loan purposes
  • Handles various credit scores from fair to bad
  • Streamlined online comparison tool
Cons:
  • Focuses on comparison rather than direct lending

3. Credit Human

Credit Human – credithuman.com

If you prefer the stability of a member-owned institution, Credit Human offers a different approach. They provide both secured and unsecured options, allowing members to borrow as little as $500 with more traditional repayment structures. Because they operate as a credit union, they tend to focus more on your ability to repay rather than just a number on a report.

This is a good choice for a long-term planner who wants to build financial health while solving a current problem. Their terms can go up to 72 months, which makes monthly payments much easier to handle on a tight budget. Instead of a massive lump sum due in two weeks, you might pay a small, manageable amount every month to keep your cash flow steady.

Pros:
  • Member-owned structure supports community values
  • Flexible repayment terms up to 72 months
  • No credit review on certain products
Cons:
  • Requires membership to access most benefits

4. GreendayOnline

GreendayOnline – greendayonline.com

GreendayOnline is built for speed. If you are staring at a pile of bills and need an answer fast, this platform moves through the process in minutes. Their digital interface works well on mobile phones, which is helpful since many people in a pinch might be accessing these services on the go via a smartphone.

They offer installment loans from $100 up to $5000. Because they avoid hard credit checks, you can find out where you stand without hurting your credit score further. This “soft pull” approach lets you see your options before you make a final commitment, which is vital if you are cautious about your financial standing.

Pros:
  • Fast approval decisions
  • No hard credit checks required
  • Funds can arrive as soon as the same day
Cons:
  • Strictly online process may lack personal touch

5. Loanz

Loanz – loanz.com

Loanz focuses on debt consolidation. If your financial struggle comes from juggling too many different monthly payments—like multiple credit cards and a medical bill—this lender helps you pull those into one manageable slice. By consolidating, you trade several chaotic due dates for one single, predictable payment.

With loan amounts up to $10,000, they offer a way to regain some control. It is a strategic choice for someone looking to reorganize their financial future rather than just looking for a quick fix. Instead of just trying to “get by,” you are working toward a more organized life.

Pros:
  • Strong focus on debt consolidation
  • Higher loan limits up to $10,000
  • Versatile for weddings, travel, or home improvements
Cons:
  • May require more documentation for higher amounts

6. OppLoans

OppLoans – opploans.com

OppLoans works through a network of bank partners. One of their most useful features is the ability to apply without affecting your FICO score. That is a huge relief for anyone watching their rating closely. Most lenders perform a “hard inquiry” that can drop your score, but OppLoans avoids that during the initial phase.

They offer same-day funding for people in a bind. It is a practical option for a consumer who needs a quick bridge to reach their next paycheck without the stress of a hard inquiry. This makes them a strong choice for short-term gaps that only require a few hundred or a few thousand dollars.

Pros:
  • Applying does not impact FICO scores
  • Same-day funding availability
  • Simple and transparent application process
Cons:
  • Approval is based on bank partner criteria

The True Cost of Subprime Borrowing

Check the math before you sign anything. Subprime lending usually carries higher Annual Percentage Rates (APRs) than traditional loans. A 10% APR might be normal for a prime borrower, but subprime rates can be much higher. This isn’t a scam, it’s just a reflection of the risk the lender takes by lending to someone with a history of late payments.

Don’t just look at the monthly payment. If you borrow $1,000 and the payment is $150, it looks affordable. But if you pay that for 12 months, you’ve paid $1,800 total. That $800 difference is the price of convenience. Always use an APR calculator to see the total cost of the loan over its entire life to avoid sticker shock at the end.

How to Apply Safely

To keep your debt manageable and increase your chances of getting approved, follow these steps:

  1. Identify the Exact Need: Figure out exactly how much you need. Borrowing $2,000 when you only need $1,200 is a mistake that just increases your interest costs.
  2. Check Your Score First: Use a free service to see your own score. This helps you decide if you need a “no credit check” option or if you can qualify for a cheaper, traditional loan.
  3. Compare the Total Cost: Look at the “Total Repayment Amount” rather than just the “Monthly Payment” to see the real impact on your wallet.
  4. Read the Repayment Schedule: Make sure the due dates align with when you get paid. If you get paid on the 1st and 15th, a loan due on the 22nd might cause problems.
  5. Verify the Lender’s Credentials: Make sure you are on a secure site with “https” and the padlock icon before you enter any sensitive bank details.

Lending in Pennsylvania

Choosing a lender shouldn’t be a whim. While instant cash sounds great, you have to read the fine print. A loan that solves a $500 problem today could become a $5,000 problem next year if you don’t understand the terms. The difference between an installment loan and a payday loan is the difference between a controlled climb and a freefall.

Don’t just focus on how fast the deposit arrives. Check if the lender uses hard or soft credit pulls. If you are already struggling, the last thing you want is another hard inquiry on your report. Too many inquiries in a short time can signal to banks that you are desperate for cash, which can drive your score down even further.

Think about why you need the money. If you are consolidating debt, a long-term installment loan like those from Loanz might be smarter than a high-interest payday advance. Match the tool to the task. Use short-term tools for quick gaps, and use long-term tools for structural financial changes.

Categories
Uncategorized

The 4 Best Lenders for Manufactured Home Financing in 2026

Manufactured home financing

The 4 Best Lenders for Manufactured Home Financing in 2026

Last updated: 2026-10-17

Finding a place to call home often feels like running a marathon through a thunderstorm. For many, that dream home is a manufactured residence, but walking into a traditional bank can feel like hitting a brick wall. If you have encountered a “no” from standard lenders, you are certainly not alone in this struggle.

The complexity of the manufactured housing sector means that the financing process is rarely a straight line. It is a labyrinth of varying regulations, property classifications, and lender appetites. You have to know exactly what you are looking at before you sign anything.

Selecting the right lender depends entirely on your unique financial footprint. Some buyers need high-speed cash for quick repairs, while others require specialized programs designed specifically for mobile homes. Navigating these waters requires knowing which institutions specialize in your specific credit profile and housing type.

For instance, if you are purchasing a home on leased land, your financing needs will differ vastly from someone who owns the land beneath a manufactured home. Understanding this distinction is the first step toward successful homeownership.

  1. FastLendGo
  2. Triad Financial Services
  3. Sound Community Bank
  4. Fannie Mae

Evaluating the 2026 Manufactured Home Lending Landscape

The criteria for this evaluation focus on specialized product availability and accessibility. A lender’s ability to look beyond a simple credit score is paramount in this niche market. We looked at how these providers handle various credit tiers, from high-income professionals to those rebuilding their financial lives.

In 2026, the landscape has shifted toward more data-driven underwriting. This means that a single mistake in your digital financial footprint can impact your eligibility across multiple platforms. It is no longer just about what a human loan officer thinks of your history.

We also weighed the importance of loan structure and speed. In a fast-moving real estate market, waiting weeks for an answer can kill a deal. Therefore, we prioritized lenders that offer clear paths for different borrower needs, whether that involves traditional mortgage backing or specialized chattel financing.

We specifically looked at the distinction between “chattel loans”—which treat the home as personal property—and “real property” loans, where the home and land are bundled together. The latter often offers lower interest rates but requires much stricter documentation and a higher credit threshold.

Lender Name Loan Types Max Loan Amount Min Credit Score Key Feature
FastLendGo Personal Loans See site See site Quick access to cash
Triad Financial Services Manufactured/Mobile See site See site Specialized financing
Sound Community Bank Manufactured Home $350,000 640 FDIC-Insured
Fannie Mae Single-Family See site See site Desktop Underwriter

Understanding the Critical Distinction: Chattel vs. Real Property Loans

Before you begin your applications, you must understand the two primary ways manufactured homes are financed. This is the most frequent source of confusion for first-time buyers. If you don’t get this right, you might face significant delays in the closing process.

It is better to sort this out now rather than discovering a problem when you are ready to move in. The difference between these two loan types changes everything from your interest rate to how you pay the loan back.

What is a Chattel Loan?

A chattel loan is essentially a personal property loan. It is used when the manufactured home is considered a piece of personal property rather than real estate. This is most common when the home is located in a mobile home park where you lease the land from a park owner.

Because the home is not tied to land you own, the lender views the loan more like an auto loan or a high-end personal loan. These loans are often easier to qualify for if your credit is less than perfect. However, they typically carry higher interest rates and shorter repayment terms, such as 10 to 15 years rather than 30.

What is a Real Property Loan?

A real property loan is a traditional mortgage. This is only an option if the home is permanently affixed to land that you (or a co-borrower) own. In this scenario, the home and the land are combined into a single piece of real estate.

This is the “gold standard” for financing because it offers the lowest interest rates and the longest terms. However, the requirements are much more stringent. You will likely need a formal appraisal that accounts for both the structure and the land, and your credit score will need to meet the higher thresholds set by institutions like Sound Community Bank.

Top Ranked Lenders for Manufactured Home Financing

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo operates as a versatile partner for those needing quick access to cash. Instead of getting bogged down in the complexities of a mortgage, this provider focuses on personal loans that can be used for various needs. It is an ideal choice for those needing to bridge a financial gap quickly.

You might use this to cover the security deposit on a new property or to fund urgent structural repairs on a home you have just acquired. (fastlendgo.com)

This lender caters to a massive spectrum of borrowers. You might find yourself looking for a small $500 loan for an emergency or a larger $5,000 sum for a specific project. They offer tailored solutions for high-income individuals as well as those with less-than-perfect credit histories.

This flexibility makes them a valuable tool in a borrower’s “financial toolkit,” even if they aren’t your primary long-term mortgage provider.

Pros:

  • Extremely fast access to cash for emergencies.
  • Flexible loan amounts ranging from $500 to $5,000.
  • Options available for various credit tiers.

Cons:

  • Personal loan structures may differ from traditional home mortgages.

2. Triad Financial Services

Triad Financial Services – triadfs.com

If you have been told “no” by traditional banks, Triad Financial Services might be the breath of fresh air you need. They specialize in what other lenders won’t touch, specifically manufactured and mobile homes. They have been in the game for over 65 years, providing stability in a volatile market.

Their longevity is a sign of their ability to handle the specific risks associated with manufactured housing. Many other lenders retreat when they see these specific property types, but Triad stays in the fight.

This lender is a specialist in the field of chattel loans. They understand the nuances of manufactured property better than a generalist bank. They know how to evaluate the depreciation of the structure and the specific ways that manufactured homes hold value differently than site-built homes.

If your goal is to secure a home despite a complicated financial past, their experience becomes an invaluable asset during the application process.

Pros:

  • Decades of experience in specialized home financing.
  • Focuses on manufactured homes where others hesitate.
  • Designed for those facing financial hardships.

Cons:

  • Specialized lending may come with different terms than standard mortgages.

3. Sound Community Bank

Sound Community Bank – soundcb.com

Sound Community Bank offers a more traditional banking experience for those purchasing manufactured homes. They provide structured loans with a clear set of requirements. This is a solid option for a buyer who has established their credit and wants the security of an FDIC-insured institution.

Working with a bank like this provides a sense of stability. Your funds are protected under the full faith and credit of the U.S. Government, which offers peace of mind during a major life transition.

The program includes specific parameters, such as a 10% minimum down payment and a minimum FICO score of 640. With loan amounts reaching up to $350,000, they provide a significant amount of breathing room for those looking to make a substantial investment in their property.

Because this is a “real property” style approach, it is highly recommended for those who intend to stay in their home for the long term and want to build equity through traditional means.

Pros:

  • FDIC-insured with the full faith of the U.S. Government.
  • Substantial loan amounts up to $350,000.
  • Clear, predictable lending criteria.

Cons:

  • Requires a minimum credit score of 640.

4. Fannie Mae

Fannie Mae – singlefamily.fanniemae.com

Fannie Mae acts as a massive engine behind the scenes of the American housing market. While they are not a direct lender you walk into on a street corner, their technology and standards drive how many loans are actually made. They provide the framework that many professional lenders use to approve you.

When you hear a lender say they “follow Fannie Mae guidelines,” it means they are using a standardized, highly regulated process. This approach minimizes risk for both the lender and the borrower, making the whole system more predictable.

Their Desktop Underwriter system is a cornerstone of modern mortgage processing. By using advanced data and insights, they help lenders make faster, more accurate underwriting recommendations. This is the gold standard for those looking for highly regulated and standardized single-family financing options.

It reduces the “human error” element of mortgage approval. The result is a more clinical and predictable outcome for the borrower, which can take some of the anxiety out of the process.

Pros:

  • Utilizes advanced Desktop Underwriter technology.
  • Provides massive scale and stability to the market.
  • Offers streamlined pricing through modern credit models.

Cons:

  • Not a direct lender; you must work through a partner.

Preparing Your Financial Portfolio for Approval

Securing a loan for a manufactured home requires more than just a decent credit score; it requires a meticulous level of documentation. Because manufactured homes are often categorized differently than stick-built homes, lenders will be particularly eagle-eyed regarding your ability to repay and the collateral value of the home.

Start by gathering your “Big Three” documents: proof of income, tax returns, and asset statements. For manufactured home buyers, lenders often want to see at least two years of consistent employment history. This consistency proves you can handle the monthly payments over the long haul.

If you are self-employed, prepare for a much deeper dive into your cash flow. You may need to provide several months of bank statements to prove that your income is stable and not just a seasonal spike. Additionally, ensure your debt-to-income (DTI) ratio is as low as possible. Most lenders want to see that your total monthly debt obligations do not exceed 43% of your gross monthly income.

Navigating Your Path to Homeownership

The most common mistake people make is applying for the wrong type of loan for their specific property. A manufactured home is often treated differently than a site-built house. If you apply for a traditional mortgage for a mobile home, you might run into a wall of confusion and delays.

Always ask your potential lender, “Will this be a real property mortgage or a chattel loan?” before you submit a formal application. Knowing this early saves you weeks of frustration and wasted paperwork.

Another pitfall is ignoring the fine print regarding credit scores. Some lenders, like Sound Community Bank, have a specific floor for credit scores. If you fall even a few points below that mark, you might be wasting your time with that particular institution.

It is worth noting that while a score of 640 might get you through the door at one bank, a score of 680 or higher might unlock much more favorable interest rates at another. Always verify your score and the specific models lenders use before you start the paperwork.

Finally, do not wait until the last minute to check your credit. A sudden dip in your score can turn a “yes” into a “no” overnight. This can happen due to a high credit card balance, a small unpaid medical bill, or even a recent inquiry for a new line of credit.

Take the time to clean up your profile, resolve any discrepancies in your credit report, and understand exactly what you bring to the table before you start knocking on doors. A clean, organized profile is your greatest leverage in a negotiation.

Categories
Uncategorized

Six Best Lenders for a Personal Loan With Collateral in 2026

Personal loan with collateral

Six Best Lenders for a Personal Loan With Collateral in 2026

Last updated: 2026-10-17

Walking into a secured loan discussion can feel like trying to find a flashlight in a thick fog. When you use an asset like a car or a savings account to back a loan, you are making a serious promise. It is a smart move for anyone looking to snag lower interest rates or get approved when traditional banks say no.

By putting up collateral, you tell the lender that their risk is much lower. This often leads to better terms and higher borrowing limits than an unsecured loan would ever allow. You are essentially trading a piece of your property for more favorable financial conditions.

Choosing a lender requires looking past the shiny marketing. You have to weigh how quickly you need the cash against the risk of losing your property. A sudden engine failure in a vehicle used as collateral or a dip in the stock market can change your loan math overnight.

This list highlights the top players in the 2026 market. We focused on companies that offer stability and speed for different financial needs.

  1. JetzLoan
  2. Best Egg
  3. OneMain Financial
  4. Freedom First Credit Union
  5. Balance Credit
  6. Synchrony

How These Lenders Were Evaluated

We wanted to find lenders that actually use collateral to help a borrower’s profile. Our team looked at how these institutions handle different credit scenarios. This included people with perfect histories and those currently struggling to stay afloat.

It is not just about the total amount of money on the table. The speed of the transaction matters just as much. A lender that makes you wait weeks for paperwork is rarely helpful when you are facing a time-sensitive bill.

Speed of funding, maximum limits, and application ease were our primary metrics. We also checked if a lender requires a hard credit pull during the first inquiry.

Being able to see your potential terms without dinging your credit score is a massive advantage. We specifically looked for lenders offering “soft pulls” for initial quotes. This allows you to shop around without seeing a trail of inquiries on your credit report.

Lender Name Max Loan Amount Funding Speed Credit Impact on Inquiry
JetzLoan $35,000 As little as 24 hours No hard credit pull
Best Egg $50,000 See site See site
OneMain Financial $30,000 As soon as 1 hour No credit score impact
Freedom First Credit Union See site See site See site
Balance Credit $4,000 Next business day No impact on credit score
Synchrony See site See site See site

Top Rated Lenders for Secured Funding

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works like a high-speed bridge for people who need cash without the usual waiting games. They connect borrowers with top lenders in just a few minutes. This makes them a great choice for emergencies.

If you need money for an urgent medical bill or an unexpected home repair, their ability to deposit funds within 24 hours is hard to beat. (jetzloan.com)

This lender is great if you are wary of the “credit score dance.” They offer a way to check your rate without a hard credit pull. You can explore options without fearing a lower score.

This is vital if you plan to apply for a mortgage or an auto loan soon. You cannot afford any fluctuations in your credit profile right now. It is a transparent, digital-first approach.

Pros:

  • Funds deposited as quickly as 24 hours.
  • No hard credit pull during the initial check.
  • High maximum loan limit of $35,000.

Cons:

  • Acts as a connector rather than the sole lender.

2. Best Egg

Best Egg – bestegg.com

Best Egg is a heavyweight in the personal loan space. They are known for a straightforward approach. They offer products designed to help users consolidate high-interest debt.

If you are carrying multiple balances on high-interest credit cards, a single Best Egg loan can merge them into one manageable monthly payment. You often see a significantly lower APR this way.

One interesting feature is their ability to use household fixtures as collateral. You can use things like cabinets or vanities. This unconventional method can open doors for homeowners who might otherwise struggle.

It is a specialized form of secured lending. It treats home improvements as an asset, providing a pathway for equity-based borrowing without the complexity of a full home equity loan.

Pros:

  • High loan amounts up to $50,000.
  • Potential for 20% APR savings.
  • Homeowner discounts available.

Cons:

  • Terms and rates are subject to specific eligibility.

3. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those who want a mix of digital ease and physical presence. With over 1,300 branches, they offer a human touch. Many online-only lenders simply cannot compete here.

If you get stuck in a digital loop or struggle to upload documents, you can walk into a branch. You can talk to a real person face-to-face. This physical presence provides a layer of security that purely digital fintechs often lack.

They are a standout choice for borrowers with less-than-perfect credit. You can see your options in five minutes without a credit score impact.

For urgent needs, like a car repair that prevents you from getting to work, they can provide funds as soon as one hour after signing. This speed is vital in “make or break” financial moments.

Pros:

  • Extremely fast funding (1 hour post-signing).
  • Extensive branch network for in-person support.
  • Flexible terms from 24 to 60 months.

Cons:

  • Maximum loan amount is capped at $30,000.

4. Freedom First Credit Union

Freedom First Credit Union – freedomfirst.com

Freedom First Credit Union operates with a community-centric mindset. This sets them apart from big-box banks. They offer secured personal loans where you can use share accounts or certificates as collateral.

This is a stable way to build credit while accessing capital. Because you are borrowing against your own savings, interest rates are typically much lower. The approval process is often simpler since the risk to the credit union is minimal.

They also provide perks like early access to paychecks through direct deposit. This flexibility helps with cash flow management. You can time your payments more effectively against your income cycle.

For those who value local involvement, their “Play for Purpose” programs show a commitment to local causes. It fosters a sense of mutual benefit between the institution and its members.

Pros:

  • Community-focused service model.
  • Options to use share accounts as collateral.
  • Perks like getting paid up to 2 days early.

Cons:

  • Likely requires membership through specific criteria.

5. Balance Credit

Balance Credit – balancecredit.com

Balance Credit is a specialized option for those needing quick, smaller amounts of cash. They offer loans up to $4,000. This makes them a niche player compared to the giants.

Their focus is on inclusivity. They review applications even for those with less-than-perfect credit. This makes them a vital resource for short-term liquidity needs where a massive loan isn’t necessary.

Their process is incredibly fast. Money can hit your account by the next business day. One of their most attractive features is the lack of penalties for paying off a loan early.

This can save you significant interest over time. If you get a tax refund or a bonus, you can wipe out the debt immediately. You won’t face “prepayment penalties” like you might at larger banks.

Pros:

  • No penalties for early loan payoffs.
  • Inclusive consideration for various credit levels.
  • Quick application process.

Cons:

  • Relatively low maximum loan amount of $4,000.

6. Synchrony

Synchrony – synchrony.com

Synchrony operates primarily through marketplace and financing models. They are often tied to specific retail brands. This makes them a specialized choice rather than a general-purpose lender.

They are the go-to for people looking to finance specific purchases through retail partnerships. For example, if you are buying high-end appliances, Synchrony might offer 0% interest promotional periods.

They offer various services, including credit cards and marketplace financing. While they might not be your first choice for a general cash infusion for utility bills, their specialized financing is excellent for large purchases.

Their integration into major retailer checkouts makes the transition from “browsing” to “financing” almost instantaneous. It is a very smooth experience for targeted credit options.

Pros:

  • Strong retail-specific financing options.
  • Diverse range of credit products.
  • Part of a large, established financial ecosystem.

Cons:

  • Less focused on general-purpose personal loans.

Understanding Collateral Types and Risks

Before committing to a secured loan, you must understand exactly what you are offering. Collateral generally falls into three categories: liquid assets, physical property, and financial instruments. Each has a unique risk profile.
Liquid assets, like savings accounts or CDs, are the safest for the lender. They are often the cheapest for you too. If you use $5,000 in a savings account as collateral, the interest rate is typically very low.

The downside is that the money is “locked.” You cannot use that $5,000 for other expenses while the loan is active. This effectively reduces your available cash reserves when you might need them most.

Physical property, specifically vehicles, is a very common form of collateral. While this allows for larger loan amounts, it introduces “depreciation risk.” The value of your car drops every year.

If you take out a $15,000 loan on a car worth only $12,000 due to high mileage, you are “underwater.” You owe more than the asset is worth. This creates a massive burden if you need to sell the car or default.

Financial instruments, including stocks or bonds, offer high borrowing potential. However, they come with extreme volatility. If the market takes a sharp downturn, your lender may issue a “margin call.”

They might require you to deposit more cash immediately. If you cannot, they can force the sale of your investments at a loss. This requires high financial literacy to manage safely.

The Step-by-Step Guide to Securing a Loan

Securing a loan requires a systematic approach. You want the best terms without accidentally damaging your financial health. Follow these steps to move through the process efficiently:

  • Step 1: Audit Your Assets. Before applying, list everything you could use as collateral. Note the current market value, not the original purchase price. For vehicles, check Kelly Blue Book. For home fixtures, consider replacement costs. Have your titles and statements ready.

  • Step 2: Check Your Credit Score (Soft Pull). Use the “no credit impact” features from lenders like JetzLoan or OneMain Financial. This gives you a baseline. Knowing your score helps you see if you qualify for “prime” rates or more expensive “subprime” options.

  • Step 3: Compare the APR, Not Just the Interest Rate. The interest rate is just the cost of the principal. The Annual Percentage Rate (APR) includes fees and points. A 5% interest rate with $500 in fees might be more expensive than a 6% rate with zero fees. Always use the APR for an apples-to-apples comparison.

  • Step 4: Evaluate the Repayment Timeline. A longer term, like 60 months, means lower monthly payments. This helps your monthly cash flow. However, you will pay significantly more in total interest. Calculate the “total cost of the loan” to see the real price tag.
  • Step 5: Review the Default Terms. Read the section on “remedies upon default.” You need to know how many missed payments trigger a default. Also, check how much notice the lender must give before they seize your collateral. This “grace period” is vital.

Avoiding Common Pitfalls in Secured Lending

The biggest mistake is underestimating the weight of collateral. When you put your car or savings on the line, you are telling the lender, “If I fail, you take this.” It is a high-stakes game.

You need a clear-eyed view of your budget. A common psychological trap is thinking, “I can always pay it back later.” The legal reality of a secured loan is rarely that flexible.

Always read the fine print regarding defaults. Some lenders are much more aggressive than others. Some might repossess a vehicle after a single missed payment. Others might offer a structured workout plan.

Keep a close eye on the total cost of borrowing. A lower interest rate might look enticing, but high fees can change everything. Watch out for “origination fees” taken from your loan amount upfront. You might receive $9,500 even though you signed for $10,000.

Finally, do not rush the process just because you are in a pinch. Speed is important, but taking an extra hour to compare terms can save you thousands. Use “no credit impact” checks to do your homework without consequence.

Categories
Uncategorized

7 Best Lenders for Bad Credit Loans in Illinois: 2026 Ranking

Bad credit loans illinois

7 Best Lenders for Bad Credit Loans in Illinois: 2026 Ranking

Last updated: 2026-10-16

Trying to bridge a financial gap when your credit score is struggling feels like running into a brick wall. In Illinois, the reality is often quite urgent. Whether it is a sudden medical bill or an unexpected car repair, the need for cash doesn’t care about your credit history. From the busy streets of Chicago to the quiet suburbs of Cook County and the downstate regions, financial emergencies hit hard and fast.

Traditional banks aren’t always helpful when things go wrong. If you have a history of missed payments or high debt, they often turn up their noses. This leaves a huge part of the population without a safety net when they need it most. Finding a way to cover costs becomes a matter of finding a lender that looks at more than just a number.

When you pick a lender, don’t just look at the approval. You need to know how quickly the money hits your bank account. You also need to know the total cost of the loan. A low monthly payment might look great on paper, but long terms can lead to paying double what you originally borrowed. This list covers the most reliable options for Illinois residents looking for a lifeline.

  1. IllinoisLoansToday
  2. Tower Loan
  3. OppLoans
  4. SAIL Loans
  5. AmeriCash Loans
  6. Reprise
  7. OneMain Financial

Evaluating Illinois Lending Options

We focused on two things: accessibility and transparency. We checked if every lender allows a soft credit check during the application. A hard inquiry can ding your score, which is the last thing you want when you are trying to climb out of a hole. Finding options that have “no impact” is vital for your financial health.

Every single point on your credit score matters. A single application for a loan you decide not to take could lower your ability to get a mortgage or a car loan later. It is a small detail that can cause big headaches down the road if you aren’t careful about who you apply with.

We also looked at how fast you get the money and the range of loan amounts available. Some lenders focus on small, quick cash advances for short-term needs. Others cater to larger expenses like home improvements or paying off high-interest credit cards. Our goal was to find services that offer flexibility for anyone in the Land of Lincoln.

Whether you need $500 for groceries or $15,000 for a new roof, there is likely a pathway available. We wanted to see who offers the most options for people dealing with real-world problems. This comparison helps you see which lenders fit your specific situation without any guesswork.

Lender Name Loan Amounts Credit Requirements Funding Speed
IllinoisLoansToday $500 – $50,000 No credit score impact Minutes
Tower Loan See site Established credit required See site
OppLoans $500 – $5,000 Does not affect FICO score Same-day funding
SAIL Loans Up to $4,000 Builds credit history Quick approval
AmeriCash Loans See site No credit check Same day
Reprise See site See site See site
OneMain Financial $1,500 – $30,000 See site As soon as 1 hour

Top-Rated Lenders for Illinois Residents

1. IllinoisLoansToday

IllinoisLoansToday – illinoisloanstoday.com

This service works like a massive matchmaking engine for people across the state. Instead of applying to dozens of different places, you connect with licensed lenders that specialize in various credit backgrounds. It saves a lot of time when every minute counts. Imagine a mechanic telling you your car needs an immediate repair just to get you to work on Monday morning. illinoisloanstoday.com

The platform is helpful if you are facing big expenses like HVAC repairs or medical emergencies. Because the service matches you with many providers, you aren’t stuck with the terms of just one company. You get to see what’s out there. Since the matching process doesn’t impact your credit score, you can explore without fear of damaging your standing.

Pros:

  • Wide range of funding from $500 up to $50,000
  • No impact to your credit score during the rate check
  • Covers diverse needs like debt consolidation or moving costs

Cons:

  • Matching service depends on third-party lender availability

2. Tower Loan

Tower Loan – towerloan.com

Tower Loan is a well-known name that offers several types of installment and personal loans. You can find options for vacations, home improvements, or auto-secured loans. An auto-secured loan can often lead to better interest rates. This happens because the vehicle acts as collateral, giving the lender more security for the money they lend you.

Keep in mind that they require an established credit history to qualify. This makes them a better fit for someone who has a shaky score but still has a documented history of managing credit. If you had a recent dip because of one late payment but have a steady income, Tower Loan might be a viable path for you.

Pros:

  • Multiple loan types including auto-secured options
  • Available in various Illinois locations
  • Established brand with a long history

Cons:

  • Requires established credit to qualify

3. OppLoans

OppLoans – opploans.com

OppLoans uses a model that looks past the numbers on a credit report. They work with bank partners to provide a platform for people who get turned down elsewhere. They use an algorithm that evaluates your ability to repay based on your income and stability rather than just a FICO number.

The application process is very lean. Decisions often arrive in just a few minutes. If you are in a pinch, getting funds as soon as the same business day can change everything. This is helpful for avoiding late fees on utility bills or rent, which prevents even more financial stress later on.

Pros:

  • Same-day funding is available for approved users
  • Applying does not affect your FICO score
  • No hidden fees in the process

Cons:

  • Loan amounts are capped at a lower $5,000 limit

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans takes a different approach by focusing on credit building. Their installment loans are designed to give you cash today while helping you build a better financial profile for tomorrow. It is a two-in-one solution for those on a tight budget. It helps bridge the gap between high-interest debt and long-term health.

They offer quick approval for those needing up to $4,000. By using their tools, borrowers can work on their financial wellness while addressing an immediate need for extra funds. This is ideal if you need a small cushion to get through the month but want to make future big purchases easier to finance.

Pros:

  • Helps build credit history and savings
  • Fast, secure online application
  • Up to $4,000 available for installment loans

Cons:

  • Specific focus on credit building may not suit those needing massive lump sums

5. AmeriCash Loans

AmeriCash Loans – americash.com

AmeriCash Loans is a rapid-response option for short-term cash needs. They follow a “money today, momentum tomorrow” philosophy. Their marketplace model allows you to send your info to lenders to see who is willing to help. This maximizes your chances of finding a lender that fits your specific credit profile.

The process is built for speed. You can often get an instant approval decision. Because they offer installment loans without a strict credit check requirement, they are a common stop for people in high-pressure situations. You won’t have to wait three to five business days for a bank’s decision when you need cash now.

Pros:

  • Fast application with instant decisions
  • No credit check required for many options
  • Same-day cash availability

Cons:

  • The marketplace model means you are redirected to various lenders

6. Reprise

Reprise – reprise.com

Reprise is a specialized platform that focuses on high-level demo creation and AI-driven tools. While it is a sophisticated piece of technology, it stands out in this list because of its focus on precision. It represents the modern evolution of SaaS tools that help businesses communicate technical concepts.

Their tools let users create high-fidelity product tours and data-injected demos. This is a very different beast compared to personal lending. It caters more to the professional enterprise space rather than the individual consumer. For a tech-savvy professional, this is a tool for productivity rather than a way to manage personal debt.

Pros:

  • Advanced AI toolset for demo creation
  • Highly capable of managing complex data payloads
  • Enables seamless sharing of product tours

Cons:

  • Not a personal loan provider for individual debt

7. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a heavyweight in the personal loan industry. They offer significant amounts for people who need them. You can access loans from $1,500 up to $30,000. This makes them ideal for larger expenses like debt consolidation, medical procedures, or major vehicle repairs that need a large upfront payment.

They offer a mix of digital convenience and human contact. They have over 1,300 branches across the country. If you prefer talking to a real person about your budget or want to discuss a repayment plan in an office, their physical presence is a huge advantage over purely online lenders.

Pros:

  • Large loan amounts up to $30,000
  • Fixed monthly payments for easier budgeting
  • Access to physical branches for personal help

Cons:

  • Requires more stringent criteria than payday-style lenders

Understanding the True Cost of Borrowing

When you are in a crisis, the need for cash can cloud your judgment. You have to understand the difference between a simple interest rate and the Annual Percentage Rate (APR). The APR is a much more accurate representation of what you will actually pay. It includes the interest rate plus any mandatory fees, like origination or processing charges.

For example, a loan with a 15% interest rate might actually have an APR of 19% once the administrative fees are added. Always look at that APR number. It is the only way to see the real price tag of the money you are borrowing from a lender.

Another critical factor is the repayment term. A short-term loan of $1,000 repaid over three months will have lower total interest costs than a $1,000 loan repaid over twelve months. Even if the monthly payments for the longer loan seem manageable, the total cost is much higher. Ask yourself if your budget can handle the worst-case scenario if your income changes next month.

If the answer is no, you might need to look for a smaller loan or a more flexible repayment structure. Planning for the worst will help you avoid a much bigger financial disaster later on.

Strategies for Managing Emergency Debt

If you take out an emergency loan, use it to stabilize your life, not make it harder. Here are a few ways to manage this kind of debt effectively:

  • Prioritize High-Interest Debt: If you use a loan to consolidate debt, make sure the new rate is significantly lower. If you use a high-interest loan to pay off a credit card, do not run up that card balance again. If you do, you will end up with twice the debt.
  • Automate Your Payments: Avoid late fees by setting up automatic payments. These fees can be devastating when you are already managing tight margins. Many lenders even offer a small discount if you set it up.
  • Negotiate with Creditors: If the emergency is a medical bill, call the hospital’s billing department first. Many Illinois healthcare providers offer interest-free plans or discounts for people facing financial hardship.
  • Build an Emergency Fund: Once the crisis is over, build a small buffer. Even saving $25 a month can eventually cover a small car repair. This prevents the need for high-interest loans in the future.

Navigating the loan process requires a balance of urgency and caution. Take a long look at the fine print before signing anything. It is easy to get caught up in the speed of an instant approval, but the actual cost of the money is what matters long term. Always check the APR and the total repayment amount.

Avoid the trap of taking a loan just because it is easy to get. If you are using a loan to pay off another debt, ensure the new loan actually has a lower interest rate. Borrowing more to pay more is a cycle that leads to a downward spiral. Use credit as a tool for stability, not a temporary bandage for a deep wound.

One common mistake is neglecting to compare offers. Just because one lender says no doesn’t mean another won’t say yes. Use the “no impact” features offered by many modern lenders to shop around without fear. This extra bit of work can save you hundreds or even thousands of dollars over the life of the loan.

Categories
Uncategorized

Top 7 Lenders for Bad Credit Loans in Georgia: 2026 Rankings

Bad credit loans georgia

Top 7 Lenders for Bad Credit Loans in Georgia: 2026 Rankings

Last updated: 2026-10-16

Trying to fix your finances in Georgia can feel like walking through a thick fog when your credit score isn’t where it needs to be. Many residents find themselves hunting for a lifeline to cover an unexpected car repair or a sudden medical bill. Unfortunately, traditional banks often shut their doors when they see a bruised credit report.

It is a stressful cycle. Without a plan, it is easy to fall into deeper debt traps while searching for quick cash. You have to be careful about where you turn when things get tight.

Finding a reliable lender involves much more than just spotting a “guaranteed” sign in a shop window. You need to read the fine print, understand how you will pay the money back, and make sure the company follows Georgia law. This list looks at the most practical options for Georgians who need extra cash and might have a less-than-perfect credit history.

  1. SkyOne
  2. Wells Fargo
  3. FastLendGo
  4. Coastline Credit Union
  5. United Bank
  6. GreendayOnline
  7. Max Cash

How We Evaluated Georgia’s Alternative Lending Options

We ranked these lenders by seeing how they treat people with bruised credit. Our focus stayed on how easy it is to apply and how much money they actually provide to someone in a pinch. Just handing out cash isn’t enough if the repayment terms are impossible to meet.

We also looked at the trade-off between speed and stability. Some lenders give you a decision instantly but charge a premium for that speed. Others take a bit longer to process but offer more predictable terms. You have to decide if you need a quick fix or a tool to help rebuild your financial standing over time.

Lender Name Loan Amounts Credit Requirements Funding Speed Key Feature
SkyOne $500 – $50,000 Credit Building Focus see site Non-Variable Rates
Wells Fargo $3,000 – $100,000 No impact to score see site Emergency Loans
FastLendGo $500 – $5,000 Bad Credit Options see site Various Loan Types
Coastline Credit Union Up to $2,500 Limited/No History see site Starter Loans
United Bank $200 – $500 No Credit Check see site 90-Day Terms
GreendayOnline $100 – $5,000 Bad Credit Welcome Same Day Quick Approvals
Max Cash $250 – $10,000+ Bad Credit Loans Minutes Title Loan Options

Ranking the Best Lenders for Georgia Residents

1. SkyOne

SkyOne – skyone.org

SkyOne works well for people who want to use debt as a ladder rather than a weight. Their personal loans are built to help you grow your credit profile while you access the funds you need. It is a smart way to fix a financial reputation through disciplined borrowing.

The non-variable rates are a major plus when the market is jumping around. Having that stability is rare in the world of high-interest lending. If you are trying to manage a larger amount, like $50,000, this is a solid option to look into.

Pros:
  • Offers non-variable interest rates for stability.
  • Focuses on credit building through personal loans.
  • High borrowing limit up to $50,000.
Cons:
  • Requires a more structured financial plan.

2. Wells Fargo

Wells Fargo – wellsfargo.com

When a major emergency hits and you need a massive influx of cash, Wells Fargo can handle it. Their emergency loans go up to $100,000, which is helpful for huge, unforeseen life events. This isn’t for someone needing a few dollars for groceries; it is for someone facing a true crisis.
One relief is that checking your options for these loans won’t hurt your credit score. You can see where you stand without fear of further damage. This is a high-ceiling option for anyone trying to weather a sudden financial storm.

Pros:
  • Very high loan limits up to $100,000.
  • No impact to your credit score during application.
  • Designed specifically for emergency expenses.
Cons:
  • Higher barrier to entry for standard approval.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a versatile choice if you find yourself in a sudden pinch. They cover everything from $500 personal loans to specialized cash for dental work or auto repairs. Think of them as a “Swiss Army knife” for various specific problems. (fastlendgo.com)

The website is built for speed. Whether you have good credit or are struggling with bad credit, they offer different paths to get cash. It is a great choice if you want to compare options quickly without jumping between dozens of different websites.

Pros:
  • Specialized loans for dental, roof, and auto repairs.
  • Covers a wide range of credit tiers.
  • User-friendly online comparison tools.
Cons:
  • Terms vary significantly based on credit.

4. Coastline Credit Union

Coastline Credit Union – coastlinecu.com

Credit unions often feel a bit more human than the massive national banks. Coastline is no different. Their starter loans are a lifeline for people with little to no credit history. These are small, manageable amounts meant to get you through the door of the financial system.

By offering loans up to $2,500, they focus on that foundational level of credit building. It is a gentle way to prove you are reliable. For a Georgian starting their financial journey, this can be a real first step toward a better economic future.

Pros:
  • Specifically designed for those with no credit history.
  • Lower barriers to entry for beginners.
  • Member-focused service model.
Cons:
  • Lower borrowing limits for those starting out.

5. United Bank

United Bank – accessunited.com

United Bank offers a very niche product called the Cash Please Loan. This is a short-term, 90-day solution for people who need a small amount of cash—between $200 and $500—without the headache of a credit check. It is a quick fix for immediate, small-scale needs.

This is perfect if you are just a few weeks away from your next paycheck but need to cover a small, urgent bill right now. It is a targeted tool for a specific type of financial gap, helping you out of a temporary bind.

Pros:
  • No credit check required for the Cash Please Loan.
  • Very quick access to small sums of cash.
  • Short-term 90-day structure.
Cons:
  • Very limited loan amounts ($200-$500).

6. GreendayOnline

GreendayOnline – greendayonline.com

When time is the enemy, GreendayOnline enters the ring. They specialize in fast funding for those with bad credit, sometimes offering same-day payouts. Their model is built for speed, letting you apply in minutes and get a decision almost instantly.
The amounts range from $100 up to $5,000, which covers most minor emergencies. It is a digital-first experience made for the modern borrower who needs an answer now rather than waiting days for a bank manager to look at a file.
Pros:
  • Potentially same-day funding.
  • Extremely fast online application process.
  • Accepts bad credit applicants.
Cons:
  • High speed often comes with high interest.

7. Max Cash

Max Cash – maxcash.com

Max Cash is a one-stop shop for high-speed products like title loans and installment loans. They offer a wide range of amounts, starting from $250 up to $10,000 or more. It is a versatile choice for anyone needing immediate relief.

The platform moves fast, promising results in minutes. They offer several ways to get cash, including options that might involve your car title, which can be a vital resource when other paths are blocked. It is a heavy-duty option for urgent liquidity.

Pros:
  • Wide variety of loan products including title loans.
  • Very fast decision-making process.
  • Large range of loan amounts available.
Cons:
  • Title loans carry significant risk of asset loss.

Making the Right Choice for Your Situation

Choosing a lender isn’t a one-size-fits-all situation. If you want to build a long-term future, you might look toward SkyOne or Coastline Credit Union. However, if you are facing a massive medical emergency, the higher limits at Wells Fargo might make more sense. You have to match the tool to the task.

Don’t rush to grab the first offer that hits your inbox. Always check for hidden fees or variable interest rates. A loan that seems cheap today can become a nightmare tomorrow if the rates jump or if you cannot keep up with a rapid repayment schedule.

Categories
Uncategorized

The Top 7 Lawn Mower Financing Options for 2026

Lawn mower financing

The Top 7 Lawn Mower Financing Options for 2026

Last updated: 2026-10-16

Buying a new mower can feel like a mountain to climb. When a professional-grade zero-turn machine hits several thousand dollars, most people don’t just walk into a dealership and hand over a thick envelope of cash. They need a way to spread that cost over several months or even years.

Whether you are replacing an aging push mower with a high-end riding tractor or expanding a commercial landscaping fleet, the method of payment matters as much as the machine itself. You aren’t just buying iron and blades; you are managing a significant capital outlay.

Finding the right lender involves more than just looking at a monthly payment. You have to weigh interest rates against how a credit check might impact your score. You also need to consider how quickly the machine actually lands in your garage.

A high-interest loan might seem manageable today. However, when stretched over a 60-month term, the total cost of ownership can skyrocket. This list evaluates the most reliable paths to ownership, from manufacturer-direct deals to fast digital loans.

  1. Cub Cadet
  2. JetzLoan
  3. Gravely
  4. K and G Mowers
  5. Manhattan Bank
  6. Minute Loan Center
  7. Yanmar

How These Financing Providers Were Evaluated

The selection process focused on accessibility and the specific needs of different types of buyers. For a homeowner looking to upgrade their yard work, a low-interest manufacturer deal is often the golden ticket. These deals sometimes include promotional periods that allow you to pay off the equipment with zero interest, provided you stay current on all payments.

Commercial landscapers have different problems. If a machine breaks down in the middle of a busy season, they need cash by tomorrow morning, not next week. For them, a three-day approval process is essentially a three-day loss of revenue. They can’t afford to wait on a slow-moving bank while their crew sits idle.

We scrutinized each entry based on funding speed, credit requirement flexibility, and term transparency. We looked at whether a lender requires a hard credit pull and how much leeway they offer for those with less-than-perfect scores. This ensures a balanced view for everyone from the casual gardener to the fleet owner.

We also considered the “total cost of credit.” This includes not just the interest rate, but also potential origination fees, documentation costs, and prepayment penalties. You don’t want to be stuck in a loan that prevents you from paying it off early when you have extra cash.

Lender Name Max Loan Amount Funding Speed Credit Requirements Key Feature
Cub Cadet see site see site see site Manufacturer Financing
JetzLoan $35,000 24 Hours No Hard Credit Pull Fast Digital Funding
Gravely see site see site Subject to Credit Fleet Pricing Available
K and G Mowers see site see site No Credit Impact Prequal 0% APR for 48 Months
Manhattan Bank see site see site see site FDIC-Insured
Minute Loan Center see site Same Day Fair Credit Accepted Instant Online Approval
Yanmar see site see site see site Global Brand Support

Ranking of Top Mower Financing Options

1. Cub Cadet

Cub Cadet – cubcadet.com

Cub Cadet offers a direct route to high-end equipment like the Ultima Series zero-turn mowers. Their financing aims to get you from the showroom floor to your first pass in record time. It is a straightforward way to acquire premium machinery without a massive upfront hit to your savings.

Because they are the manufacturer, the financing is often integrated directly into the point of sale. You don’t have to deal with a third-party bank that doesn’t understand the specific value of the equipment you are buying. It keeps things simple and localized to the brand.

This option works well for the homeowner who knows exactly which model they want and wants to stay within the brand ecosystem. Whether you need a riding mower or a snow blower, the financing is tailored to the specific equipment you are eyeing. Many deals include “no money down” options, which is ideal for seasonal workers who want to preserve their cash for fuel and maintenance.

Pros:
  • Direct manufacturer support
  • Options for specialized equipment
  • Streamlined application process
Cons:
  • Terms are subject to specific model availability

2. JetzLoan

JetzLoan – jetzloan.com

When speed is the name of the game, JetzLoan stands out. They specialize in getting funds deposited into your account in as little as 24 hours. This is a lifesaver if your current mower kicks the bucket in the middle of a busy season.

In the landscaping business, a broken mower isn’t just an inconvenience; it is a halted revenue stream. JetzLoan fills that gap by providing liquidity when traditional banks might take a week to process the paperwork. It is built for the person who needs to keep working.

They offer loans up to $35,000 and do not perform a hard credit pull during the initial check. You can see your rate without any fear of a temporary dip in your credit score. This “soft pull” technology is essential for buyers who want to shop around and compare monthly payments before committing.

Pros:
  • Extremely fast 24-hour funding
  • No hard credit pull for initial rates
  • High maximum loan limit
Cons:
  • Digital-first approach may lack personal interaction

3. Gravely

Gravely – gravely.com

Gravely is a heavy hitter for those who treat lawn care as a professional vocation. Their financing options are built for longevity and serious business. They even offer specialized fleet pricing for pros looking to grow their entire crew’s capabilities.

Unlike consumer-grade financing, Gravely’s options often account for the higher depreciation and higher usage rates of commercial machines. They understand that a commercial mower is a tool that works much harder than a residential one.

If you are looking to outfit a fleet of commercial zero-turn mowers, Gravely provides the structural support to make that happen. They focus on the professional who needs equipment that works as hard as they do. This might include tax-advantaged leasing options or specialized business lines of credit as your client list grows.

Pros:
  • Excellent fleet pricing programs
  • Designed for commercial-scale use
  • Strong brand reputation
Cons:
  • Credit approval is strictly required

4. K and G Mowers

K and G Mowers – kgmowers.com

K and G Mowers provides an aggressive deal for those looking to maximize their purchasing power. They offer 0% APR financing for up to 48 months on various mowers and tractors. This is a massive advantage for someone wanting to keep their cash liquid while still getting new gear.

At 0% APR, every dollar you pay goes directly toward the principal of the machine. You aren’t being eaten up by interest charges that can add hundreds or even thousands to the total price. It is a very efficient way to use your money.

Their process is user-friendly, allowing you to get prequalified without a credit impact. Based in Paris, TX, they also provide local delivery and in-house service. This hybrid model—combining online prequalification with local, physical service—is ideal for buyers who want modern fintech convenience with the security of a brick-and-mortar business.

Pros:
  • 0% APR for up to 48 months
  • No credit impact prequalification
  • Local delivery and service available
Cons:
  • Physical location is localized to Texas

5. Manhattan Bank

Manhattan Bank – manhattanbank.com

For those who prefer the security of a traditional institution, Manhattan Bank offers a stable alternative. As an FDIC-insured entity, they provide the peace of mind that comes with working with a bank backed by the U.S. Government. This is vital for large-scale commercial purchases.

If you are seeking a high-limit business loan that requires deep scrutiny of your company’s financial history, a bank is often the right path. They offer personal and business loans for many different occasions, catering to various needs.

While it might not be as “instant” as a fintech app, the stability and professional oversight of a bank can be vital for complex financing. If you are planning to build a massive equipment warehouse or purchase multiple heavy tractors, a relationship with an established bank can provide more flexible long-term lines of credit.

Pros:
  • FDIC-insured security
  • Personal and business loan options
  • Established banking reputation
Cons:
  • Likely slower than instant digital lenders

6. Minute Loan Center

Minute Loan Center – minuteloancenter.com

Minute Loan Center is the go-to for people who need money immediately and may have had a bumpy road with their credit. They focus on fast approval, even for those with fair credit, and can offer same-day deposits via direct deposit. This is perfect for emergencies.

Imagine a mower fails on a Monday and you need a new one working by Tuesday to fulfill your contracts. This is an excellent choice for that “emergency replacement” scenario. They emphasize a transparent process with no hidden fees, which helps take the stress out of a high-pressure decision.

While the interest rates might reflect the higher risk of the loan, the speed and accessibility make it a vital resource for maintaining business continuity. It is about keeping your business moving when things go wrong.

Pros:
  • Same-day loan disbursement
  • Approvals for fair credit holders
  • No hidden fees
Cons:
  • Interest rates may be higher for non-prime credit

7. Yanmar

Yanmar – yanmar.com

Yanmar represents a global standard for heavy-duty, high-quality machinery. While they are a massive international entity, their financing is about providing a way to access world-class equipment across various regions. Their structures often reflect the high resale value of Yanmar machines.

This high resale value can make securing a loan easier through specialized agricultural or commercial lenders. They are a great choice for those who want the absolute best in engineering and a brand that supports its machinery globally.

It is a long-term investment in quality that spans continents. When you finance a Yanmar, you aren’t just buying a machine; you are investing in a piece of infrastructure that is expected to serve you for a decade or more.

Pros:
  • World-class machinery quality
  • Global brand presence
  • Highly durable equipment
Cons:
  • Less focus on consumer-level quick financing

The True Cost: Interest vs. Opportunity Cost

When deciding between a low-interest manufacturer deal and a high-speed digital loan, you must weigh interest costs against opportunity costs. For example, if a manufacturer offers 0% APR for 48 months, but a digital lender like JetzLoan offers a 5% interest rate but provides the money 4 days faster, which is better for you?

If those 4 days allow you to complete three landscaping jobs that generate $1,200 in profit, then the “expensive” loan actually saved you money. The speed of the capital outweighed the cost of the interest. You have to look at the bigger picture of your cash flow.

Conversely, if you are a homeowner with a large savings account, paying cash might seem like the best move to avoid interest. However, if that cash could be earning 5% in a high-yield savings account while you only pay 3% on a mower loan, you are actually losing money by paying cash. Understanding the math is the difference between a smart purchase and a financial burden.

Common Financing Pitfalls to Avoid

Before you sign any paperwork, take a moment to breathe and look at the fine print. Many people fall into the trap of only looking at the monthly payment. A low monthly payment sounds lovely, but if it comes with a massive interest rate over five years, you will end up paying for that mower twice.

Always calculate the “Total of Payments.” Multiply the monthly payment by the number of months to see the real cost. It is a simple calculation that reveals the truth behind the marketing. You need to know exactly how much cash is leaving your pocket over the life of the loan.

Always check if the lender offers a “no credit impact” prequalification. This allows you to shop around and compare different offers from companies like JetzLoan or K and G Mowers without hurting your credit score. It is like window shopping; you want to see the price before you commit to the test drive.

Watch out for the “hidden” costs that often hide in the shadows of a contract. Some lenders might charge origination fees or high late fees if you miss a single payment. If you are buying for a business, ensure the terms align with your seasonal income.

You might want to ask specifically about “seasonal payment” options. These allow you to pay more in the summer and less in the winter—a feature many commercial lenders are willing to provide for established businesses. It keeps your finances balanced when the grass isn’t growing.

Categories
Uncategorized

The 7 Best Lenders for Tractor Financing in 2026

Tractor financing

The 7 Best Lenders for Tractor Financing in 2026

Last updated: 2026-10-16

Securing enough capital to keep a farm running often feels more taxing than the actual harvest. Whether you need a new fleet of combines for a large-scale operation or a single utility machine for a small hobby farm, the terms you sign today will dictate your cash flow for years. It is a high-stakes game of math and timing.

One miscalculated interest rate or an unexpected balloon payment can throw your seasonal budget into chaos. You don’t want a year of hard work to spiral into a permanent cycle of debt. Choosing a lender is less about finding a transaction and more about finding a partner that won’t become a barrier to your success.

When weighing your options, pay attention to how flexible the terms are and how fast the cash arrives. You should also consider how a lender treats your specific credit history. You might be tempted by the speed of a digital approval, but don’t ignore the long-term stability and lower rates often found at established, brick-and-mortar institutions.

  1. Mahindra
  2. FastLendGo
  3. AgDirect
  4. Yanmar
  5. Manhattan Bank
  6. VivaLoan
  7. Roadrunner Financial

How These Financing Options Were Evaluated

We looked across a wide spectrum of agricultural needs to pick these lenders. Our list includes everything from specialized equipment manufacturers to community-focused banks. We wanted a mix of speed, accessibility for different credit scores, and the ability to handle various types of machinery. We didn’t just read marketing brochures; we looked at how these lenders fit into the actual lifecycle of a farm.

Speed of decision-making and collateral requirements were our primary metrics. Some lenders excel at rapid digital applications using “soft” pulls that won’t ding your credit. Others offer the heavy-duty, long-term stability you get through secured loans from traditional banks. We also looked at the “niche” factor—whether a lender is built for high-value tractors or for the quick cash needed for seasonal repairs.

This variety ensures there is a match for every situation, whether you are looking to buy a $200,000 harvester or a $5,000 utility trailer. Every farm has a different rhythm, and the financing needs to match that pace. You shouldn’t have to fit your business into a lender’s rigid box.

Lender Name Loan Amounts Funding Speed Credit Requirements Terms/Specialty
Mahindra see site see site 550 FICO minimum 6-year warranty options
FastLendGo $500 – $5,000+ Fast access All credit types Personal financing focus
AgDirect see site Seconds for most See site New and used equipment
Yanmar see site see site see site Global availability
Manhattan Bank see site see site see site Personal and business
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome Small personal loans
Roadrunner Financial see site Real-time decision All credit scores Powersports focus

Top-Tier Agricultural Lenders

1. Mahindra

Mahindra – mahindratractor.com

Mahindra has built a massive reputation in the tractor industry. They offer specialized financing for many different needs, which is helpful if you might struggle to meet traditional bank requirements. It is a solid choice if you want a brand with deep roots in the farming community, providing the kind of security that comes with manufacturer-backed terms.

The company provides options for people with a minimum credit score of 550 FICO. This makes it a viable path for those with a limited credit history or anyone who has seen a temporary dip in their score due to seasonal fluctuations. Their dealer network makes the process easier, often allowing for on-site consultations and direct applications right at the dealership.

Pros:

  • Low entry barrier with 550 FICO minimum
  • Covers those with limited credit history
  • Strong brand reputation and presence

Cons:

  • Credit approval is subject to specific terms

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a versatile option for anyone needing quick access to cash. While they cover a wide range of personal loans, their speed makes them a useful tool for immediate operational needs. This includes things like buying fuel in bulk or paying for emergency repairs that don’t fit into your standard operating costs. (fastlendgo.com)

If you find yourself facing an unexpected repair or a sudden need for working capital, this lender moves fast. They cater to a broad demographic, including those with bad credit or high-income individuals looking for specific loan structures. Their model relies on high-speed digital processing, which is perfect for the modern farmer who cannot afford to wait weeks for a bank committee to meet.

Pros:

  • Extremely fast access to cash
  • Covers various states across the US
  • Flexible for bad credit scenarios

Cons:

  • Primarily focused on personal loans rather than specialized ag-equipment

3. AgDirect

AgDirect – agdirect.com

AgDirect is a heavyweight in the world of specialized farm equipment financing. They provide options for both new and used machinery, whether you are buying from a dealer, an auction, or a private party. This flexibility is a massive advantage if you find a great deal on a used implement at a local auction and need financing that moves as fast as the auction hammer.

Their digital process is impressively quick. Most applications get a credit decision in seconds, allowing you to move on a piece of equipment before a competitor grabs it. This “instant” aspect is vital in a market where high-demand machinery can sell within hours. It is a modern way to handle agricultural lending, cutting out the friction of physical paperwork.

Pros:

  • Ultra-fast credit decisions for most
  • Covers new, used, and private sales
  • Seamless online application process

Cons:

  • Primarily focused on equipment rather than general cash flow

4. Yanmar

Yanmar – yanmar.com

Yanmar is a global name that brings international expertise to the table. They serve a massive range of regions, from the United States to Europe and Asia. This makes them a reliable choice for those who want a manufacturer with global reach and a standardized level of service.

When you work with a manufacturer-aligned lender, you deal with people who understand the specific value of the machinery. They know a tractor’s utility is tied to the season, so they may offer specialized terms or repayment schedules that a general bank might overlook. This alignment can lead to better terms for highly specialized agricultural implements.

Pros:

  • Massive global presence and reliability
  • Manufacturer-linked expertise
  • Diverse regional availability

Cons:

  • Highly regionalized availability for certain products

5. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank offers a more traditional, stable approach. They provide a range of personal and business loans, which is vital for established operations looking for structured banking relationships. For a farm that has been running for decades, a stable banking partner is often more important than a quick loan.

If you prefer speaking with a human being, you can talk directly to a loan officer here. This is incredibly helpful when navigating complex business loans, like land purchases or large-scale facility upgrades. Being able to walk into a branch and explain your specific agricultural cycle provides a level of comfort that purely digital lenders cannot match.

Pros:

  • Option to speak with a loan officer directly
  • FDIC-insured stability
  • Offers both personal and business products

Cons:

  • May require more traditional documentation than fintech lenders

6. VivaLoan

VivaLoan – vivaloan.com

VivaLoan is built for the person who needs money quickly without a mountain of paperwork. They specialize in small personal loans, ranging from $100 up to $15,000. This is an agile way to bridge a small financial gap, like a sudden part failure that requires an immediate purchase from a supplier.

Speed is the main selling point here, with funds potentially available as soon as the next business day. For a farmer needing a quick fix for a small piece of equipment or an unexpected expense like a vet bill, this is very efficient. It fills the gap between using a credit card and taking out a major commercial loan.

Pros:

  • Extremely fast funding, often by the next day
  • Low minimum loan amounts
  • Welcomes all credit types

Cons:

  • Loan amounts are relatively small for major machinery

7. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a specialized player focused on the powersports and smaller utility vehicle market. They are an excellent choice if your “tractor” needs involve ATVs, side-by-sides, or golf carts used for farm tasks. Many modern farms rely heavily on these smaller, mobile vehicles for daily operations.

They offer a streamlined pre-qualification process that does not impact your credit score. This allows you to see what you might qualify for without any immediate risk to your financial standing. You can test the waters of different financing tiers without the fear of a “hard inquiry” lowering your score right before a larger application.

Pros:

  • No credit score impact to check rates
  • Specialized in utility/powersports vehicles
  • Quick real-time decisions

Cons:

  • Limited to specific vehicle types like ATVs and side-by-sides

Understanding the True Cost of Borrowing

Many farmers make the mistake of looking only at the monthly payment. While a low monthly payment is tempting for cash flow, you must calculate the Total Cost of Ownership (TCO) for your debt. This means looking at the interest over the entire life of the loan. A 7-year loan with a low interest rate might actually cost you $5,000 more in total interest than a 5-year loan with a slightly higher rate.

Keep these three factors in mind before you sign anything:

  • Amortization Schedule: How much of your payment goes toward the principal versus interest in the early years?
  • Prepayment Penalties: If you have a great harvest and want to pay the loan off early to save on interest, will the lender charge you a fee?
  • Variable vs. Fixed Rates: In an inflationary environment, a variable rate can become dangerous if interest rates spike. A fixed rate provides the certainty needed for long-term budgeting.

Preparing Your Financial Application

Whether you go to a local bank or an online fintech, the quality of your application determines the speed and terms you get. Lenders want to see that you are a low-risk operator with a clear plan for the capital you are requesting.

To maximize your chances of approval and better rates, follow these steps:

  1. Organize Your Financial Statements: Have your last two years of tax returns, current balance sheets, and profit and loss (P&L) statements ready. Having these ready to upload can prevent delays.
  2. Define the Asset’s Value: If you are financing equipment, have the specific make, model, year, and serial number ready. For used items, have a clear idea of the current market value.
  3. Check Your Own Credit: Don’t wait for the lender to find an issue. Check your report for errors. If you have a low score, be prepared to explain why—such as a seasonal debt cycle—to provide context.
  4. Have a Repayment Plan: Be ready to explain how this purchase will generate the revenue to pay back the loan. For example: “This new harvester will reduce labor costs by 15%.”

Selecting the Best Path Forward

Before signing any contract, look at the total cost of borrowing. Don’t just look at the monthly payment; look at the interest over the life of the loan. A lower monthly payment often means a much longer term, which can end up costing you significantly more in the long run.

Avoid the mistake of rushing into a deal just because the equipment is available. Always compare terms from a manufacturer-based lender against a local community bank. Often, the bank might offer better long-term rates, while the manufacturer offers better immediate convenience and specialized coverage.

Finally, keep your credit score in mind. If your score is on the lower side, focus on lenders like Mahindra or VivaLoan that are more accommodating to diverse credit profiles. Knowing your own financial strength before you start shopping will save you hours of frustration and help you secure the tools you need to grow.

Categories
Uncategorized

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Personal loan after bankruptcy

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Last updated: 2026-10-16

Trying to fix your finances after a bankruptcy can feel like walking through a thick fog. You might need a quick car repair to get to work, or perhaps an unexpected medical bill popped up right after your discharge. Sometimes, it is just about bridging a gap caused by a sudden change in employment. The goal is to find a lender who sees your current potential instead of just your past mistakes.

The way people borrow money has changed a lot. Where a bankruptcy once acted as a permanent “no,” modern fintech companies and community institutions are looking at your recent behavior. They care about the trajectory of your finances today rather than just the scars left on your credit report from years ago. It is about where you are going, not just where you have been.

Picking the right lender involves more than just glancing at an interest rate. You have to weigh how fast you can get the cash, what the minimum requirements are, and how much flexibility the company offers. Some providers focus on rapid cash for emergencies, while others offer structured installment plans to help you rebuild your credit over time. It is a balancing act between speed and long-term stability.

Accessibility is a tricky term that does not mean the same thing to everyone. A lender that is incredibly easy to get approved with might charge a premium for that convenience. On the other hand, a lender with stricter rules might offer the lower rates you need for long-term debt management. You have to decide whether you need a quick fix or a long-term strategy.

  1. FastLendGo
  2. SoFi
  3. Prosper
  4. Avant
  5. Allegiance Credit Union
  6. VivaLoan
  7. World Finance

Evaluating Lenders for Post-Bankruptcy Borrowing

This ranking focuses heavily on how easy it is to get approved and how fast you see the money. Financial emergencies do not wait for a perfect credit score to resolve themselves. We prioritized lenders that provide clear paths for people with different credit histories. If a delay of three days means you lose your utility service, you need a lender that moves quickly.

We also looked at the variety of loan amounts available. A lender that only offers tiny microloans might not help if you need to consolidate debt or fix a roof. Conversely, traditional banks often have massive hurdles, requiring collateral or credit scores that a post-bankruptcy borrower simply cannot reach yet. We looked for “soft” credit pulls so you can shop around without hurting your score.

Lender Name Loan Amounts Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ Quick access Bad/Fair/Good/Great
SoFi see site see site see site
Prosper $2,000 – $50,000 Fast access see site
Avant see site see site see site
Allegiance Credit Union see site see site see site
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome
World Finance see site see site see site

The Top Ranked Lenders for Rebuilding Credit

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a great option for anyone stuck in a tight spot. They offer a wide range of options, from small $500 loans to larger $5,000 packages. This flexibility is helpful if you are juggling several different needs, like a small repair for a car and a larger bill for your taxes.

The whole platform is built for speed, which is perfect if you need cash immediately. Whether you are dealing with dental bills, auto repairs, or home maintenance, they make it easy to compare local options. Traditional banks often require mountains of paperwork and multiple trips, but FastLendGo uses a digital-first approach to get things moving quickly.

It is a solid choice for a quick fix when you cannot afford to wait around for a long approval process.

Pros:
  • Wide variety of loan amounts from $500 to $5,000 and beyond.
  • Covers specific needs like auto, dental, and roof financing.
  • Accommodates various credit tiers from bad to great.
Cons:
  • May not offer the lowest rates for those with excellent credit.

2. SoFi

SoFi – sofi.com

SoFi works more like a complete financial ecosystem. While many know them for banking and investments, they offer sophisticated tools to help manage your money. Their high-yield savings accounts can help you start rebuilding your savings effectively, giving you a safe place to park cash while your credit score climbs.

By automating your savings through their platform, you can build a buffer that helps you avoid high-interest debt in the future. This lender is perfect for the person who wants to manage everything in a single place, from checking accounts to mortgages.

They are more selective than the micro-lenders, but their products are built for people who have moved past their hardest financial struggles. It is a polished option if you are looking toward long-term stability and wealth growth.

Pros:
  • Integrated banking, investing, and insurance services.
  • High APY options for savings accounts.
  • User-friendly digital platform.
Cons:
  • Typically requires a higher credit tier for the best terms.

3. Prosper

Prosper – prosper.com

Prosper gives you a look into peer-to-peer (P2P) lending. They provide substantial amounts, ranging from $2,000 up to $50,000. This makes them a heavy hitter if you need to tackle major debt or large expenses like tuition or home renovations. Because they rely on individual investors rather than a bank’s pool of money, their criteria can be different from traditional lenders.

Their platform is fast and secure. You can see your rates in about a minute through a soft credit pull. This is vital if you are worried about hurting your credit score while you are just shopping around for the best deal.

For anyone wanting to move away from standard bank loans, Prosper offers an efficient experience. It is a strong choice for large-scale financing when a traditional bank might have given you a hard no.

Pros:
  • High loan ceilings up to $50,000.
  • Quick rate checking with minimal impact to credit.
  • Fast and secure online application process.
Cons:
  • Peer-to-peer models can sometimes have variable approval rates based on investor demand.

4. Avant

Avant – avant.com

Avant focuses on helping you move your financial life forward. They offer solutions like credit cards and installment loans, which are great for proving you can make consistent, on-time payments. Their approach feels more like a partnership, providing tools to help you reach specific goals like debt consolidation.

Whether you need to combine several high-interest payments into one manageable monthly bill or you just need an emergency loan for a sudden crisis, Avant has options. They aim to provide clear answers to difficult financial questions.

Their model is tuned for the middle-ground borrower. These are people who might not have elite scores but have shown steady income and responsibility through their recent financial history.

Pros:
  • Specializes in debt consolidation and emergency loans.
  • Flexible solutions for different life stages.
  • User-focused support and tools.
Cons:
  • Specific eligibility criteria can be difficult to navigate.

5. Allegiance Credit Union

Allegiance Credit Union – allegiancecu.com

Allegiance Credit Union is a community-focused institution that has been around since 1963. They operate under the idea that every story matters, including those of people rebuilding after a setback. This approach is different from large, impersonal national banks where you are just a number on a screen.

In a credit union, your local environment and your relationship with a loan officer actually carry weight. They offer products designed to help you save, borrow, and build a stronger future. If you prefer a mission-driven banking experience, a credit union is a refreshing change.

They often provide more personalized guidance during the application. This is incredibly helpful when you need to explain why your past bankruptcy is behind you and why your current situation is stable and looking up.

Pros:
  • Strong community roots and long-standing reputation.
  • Mission-driven approach to member well-being.
  • Diverse products for saving and borrowing.
Cons:
  • Geographic limitations may apply to membership.

6. VivaLoan

VivaLoan – vivaloan.com

VivaLoan is built for speed. They offer loans starting as low as $100 up to $15,000. This wide spectrum lets you find exactly what you need, whether it is a tiny amount for new tires or a larger sum for a major life event. This flexibility is vital if you are still in the stabilization phase of your recovery.

One of their best features is the speed of funding. You can often receive your money as soon as the next business day. With a five-minute application process and an open policy for all credit types, they are a lifeline in an emergency.

While the ease of use is hard to beat, you should use these funds strategically. You want to avoid falling into a cycle of high-interest borrowing that can keep you stuck.

Pros:
  • Extremely fast funding, often by the next business day.
  • Very low minimum loan amount of $100.
  • Welcomes all credit types.
Cons:
  • High speed and accessibility can come with higher costs.

7. World Finance

World Finance – worldfinance.com

World Finance is a specialized player in the market. They offer a variety of services, including retail and private banking. Their focus often leans toward more structured financial environments and specialized segments, providing options for people who do not fit into a standard consumer lending box.

This can include people with unconventional income streams or those needing very specific loan structures. They provide a deep look into both global and local economic trends for their clients.

For those seeking a more complex financial partner, they offer services that go beyond a simple personal loan. Their expertise is useful for borrowers navigating a sophisticated recovery involving multiple asset types.

Pros:
  • Wide breadth of financial services and insights.
  • Expertise in diverse banking sectors.
  • Professional focus on market trends.
Cons:
  • May be more complex than a standard consumer lender.

Strategies for Maximizing Your Approval Odds

Securing a loan after a bankruptcy discharge requires a strategic approach. Lenders want to see “stability indicators.” Even if your score is still recovering, you can improve your odds by providing organized documentation of your income. This means having recent pay stubs, bank statements, and tax returns ready to go. A lender is much more likely to say yes if they see a clear, unbroken line of income.

Another smart move is to consider a “secured” loan if “unsecured” options are proving too difficult. A secured loan is backed by an asset, like a car title or a savings account. Because the lender has collateral, their risk is much lower, which often leads to higher approval rates and better interest rates. Once you pay that loan back, your credit score usually gets a significant boost.

This path paves the way for the larger, unsecured loans you might need later on. It is a way to prove your reliability to the banks while you are still getting back on your feet.

Common Pitfalls to Avoid During Your Search

When you are looking for a loan, the biggest mistake is rushing into the first offer you see. You must compare the total cost of borrowing, not just the monthly payment. A low monthly payment can hide a much higher interest rate or a term that is so long you end up paying double what you borrowed. Always ask for the Annual Percentage Rate (APR) to see the true cost.

Another mistake is failing to check your credit report for errors before you apply. Even after a bankruptcy is discharged, mistakes can linger. A debt that was included in your bankruptcy might still show as “unpaid” on your report. Clean up your records first to give yourself the best chance of success.

Finally, read the fine print regarding prepayment penalties. Some lenders charge a fee if you try to pay the loan off early. This is the last thing you want when you are trying to move out of debt quickly. Approach your search with patience. The journey to financial health is a marathon, not a sprint.

Categories
Uncategorized

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Holiday loans for bad credit

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season often brings a whirlwind of expenses that can catch anyone off guard. Between unexpected gifts, last-minute travel tickets, and seasonal hosting costs like grocery surges and decor, the financial squeeze can feel overwhelming. For those facing the holidays with less-than-perfect credit, finding a reliable way to bridge the gap is essential for a stress-free December.

Rather than relying on high-interest payday loans that can lead to a cycle of debt, many are turning to specialized lenders that prioritize speed and accessibility. When selecting a lender, the priority shifts from finding the lowest APR to finding speed and accessibility.

A lender that offers quick funding can be a lifesaver when a last-minute purchase is needed, such as a sudden car repair required to get home for the holidays or an unexpected catering bill for a family gathering. It is vital to look for transparency regarding fees and how the application process might impact your current credit standing.

Understanding the difference between a “hard pull”—which can temporarily lower your score—and a “soft pull”—which is essentially harmless—is the first step in making an informed decision.

  1. JetzLoan
  2. Addition Fi
  3. OppLoans
  4. World Finance
  5. Sound Credit Union
  6. OneMain Financial

How These Holiday Lenders Were Evaluated

The ranking process focused on speed, accessibility, and the ability to secure funds despite a challenging credit history. Each option was assessed based on how quickly money hits a bank account and whether the application process involves a hard credit pull. This is a crucial distinction for anyone looking to shop around without damaging their score.

We analyzed the “time-to-cash” metric, which measures the elapsed time from the moment you click “apply” to the moment the funds are available for spending in your checking account. Accessibility was also a key pillar. Lenders were evaluated on their ability to serve individuals who might be turned down by traditional banks.

Traditional banking institutions often rely heavily on FICO scores and long-term credit history, which can be a barrier for those with recent setbacks. Our evaluation looked for providers that offer clear terms, minimal hidden fees, and a straightforward path from the initial application to receiving the necessary cash for seasonal needs.

We specifically prioritized lenders that provide a “pre-qualification” step, allowing you to see potential terms before committing to a formal application.

Lender Name Max Loan Amount Funding Speed Credit Impact Terms/Rates
JetzLoan $50,000 As little as 24 hours No hard credit pull See site
Addition Fi See site See site See site See site
OppLoans See site Same-day funding available No FICO score impact See site
World Finance See site See site See site
Sound Credit Union See site See site See site
OneMain Financial $30,000 As soon as 1 hour No credit score impact Starting at 11.99% APR

Top Rated Lenders for Seasonal Funding

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with top personal loan lenders in just a few minutes. It is an ideal solution for those who need a significant amount of cash, with loan limits reaching up to $50,000. The process is designed to be incredibly fast and transparent, removing the bureaucratic red tape often found in big-box banking. (jetzloan.com)

This option is perfect for individuals who need flexibility without the fear of a credit score dip. Because there is no hard credit pull during the initial check, you can explore your options freely. This “soft inquiry” approach allows you to gauge your eligibility and potential interest rates without the risk of a score decrease.

Funds can be deposited into your account in as little as 24 hours. This makes it suitable for those facing a tight deadline, such as a holiday travel booking that is about to expire.
Pros:

  • High maximum loan amount of $50,000
  • Fast 24-hour funding
  • No hard credit pull during the rate check
Cons:
  • Connecting with lenders takes a few minutes of application time

2. Addition Fi

Addition Fi – additionfi.com

Addition Financial operates as a full-service credit union, offering a wide variety of banking products. While they provide traditional loans, their focus is on building a long-term relationship with members. They offer competitive rates designed to help people borrow smarter and save more over time.

Unlike some predatory lenders, credit unions are member-owned. This means their primary goal is to serve their community rather than maximize shareholder profits. This is a great choice for those who want more than just a quick loan. They provide checking, savings, and various investment options.

It is a more stable, community-oriented approach for anyone looking to manage their finances more holistically during the holidays. If you are planning to make a large purchase, such as a used vehicle for holiday travel, their specialized loan products might offer better terms than a general personal loan.

Pros:

  • Diverse range of banking and investment services
  • Competitive rates on various products
  • Member referral incentives available
Cons:
  • May require membership to access full benefits

3. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their platform works with bank partners to provide personal loans that consider more than just a FICO number. They look at a broader range of financial data, which is helpful for individuals who may have a high income but a low credit score due to past student loans or medical debt.

Speed is their specialty, with same-day funding available if you are approved. The application is quick and easy, often providing decisions within minutes. This makes them a streamlined option for those facing an immediate cash crunch during the holiday season, such as a sudden need for emergency home repairs before guests arrive.

Pros:

  • Same-day funding available
  • Decisions often made in minutes
  • Does not affect FICO score when applying
Cons:
  • Approval is subject to bank partner criteria

4. World Finance

World Finance – worldfinance.com

World Finance provides a broad spectrum of financial services, ranging from retail banking to specialized asset management. They offer a sophisticated approach to finance that covers everything from insurance to complex investment strategies and corporate governance. Their infrastructure is designed to handle a wide variety of financial needs, making them a versatile option for a diverse client base.

This entity is suited for individuals or businesses needing specialized financial structures rather than a simple quick cash injection. Their scope is much wider than a standard personal lender, offering deep expertise in various global economic sectors.

If your holiday needs involve more complex financial planning or business-related seasonal inventory financing, their expertise may be relevant.
Pros:

  • Extensive range of financial services
  • Expertise in multiple banking sectors
Cons:
  • May be more complex than a simple holiday loan provider

5. Sound Credit Union

Sound Credit Union – soundcu.org

Sound Credit Union serves its members with a comprehensive suite of loan products. They offer everything from personal and student loans to specialized financing for RVs, boats, and motorcycles. Their focus is on providing a variety of paths to meet different financial goals, ensuring that members have options whether they are looking for a small personal loan or a large asset-backed loan.

For those who need a specific type of loan, such as an auto or home loan, they offer a structured environment. They provide a range of services including mobile and online banking, making it easy to manage your money on the go. This is particularly useful during the holidays when you might be traveling and need to check your balance or transfer funds instantly via your smartphone.

Pros:

  • Wide variety of specialized loan types
  • Convenient mobile and online banking
  • Comprehensive service list from checking to retirement
Cons:
  • May require specific membership criteria

6. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those needing quick access to personal loans between $1,500 and $30,000. They pride themselves on offering more options than most people expect. You can often see your potential options in just five minutes without any obligation, which is ideal if you are comparing multiple lenders at once.

If you need money immediately, they offer a path to receive funds as soon as one hour after the loan is signed. With fixed monthly payments and terms ranging from 24 to 60 months, they provide a predictable way to handle seasonal expenses. This predictability is vital for budgeting; knowing exactly what you owe each month prevents any surprises when you are trying to save for January expenses.

Pros:

  • Extremely fast funding (as soon as 1 hour)
  • Fixed monthly payments for budget stability
  • Large network of 1,300 branches for personal help
Cons:
  • Interest rates can vary based on creditworthiness

Step-by-Step: How to Apply for Seasonal Funding

Securing a loan during the busy holiday season requires a methodical approach to ensure you get the best terms without unnecessary delays. Follow these steps to maximize your chances of success:

  1. Assess Your Total Need: Before applying, calculate exactly how much you need. Don’t just guess; look at your gift list, planned grocery budget, and any expected travel costs. Borrowing more than you need can lead to unnecessary interest costs.
  2. Check Your Credit Score: While many lenders offer soft pulls, knowing your score helps you set realistic expectations for the interest rates you might receive.
  3. Gather Documentation: To speed up the process, have your most recent pay stubs, proof of identity (like a driver’s license), and bank account details ready. Digital copies of these documents will significantly reduce application time.
  4. Compare Pre-Qualifications: Use the lenders mentioned above to check your eligibility. Focus on lenders that offer a “no hard credit pull” option to protect your score while you shop around.
  5. Review the Total Cost: Look beyond the monthly payment. Check the “Total Repayment Amount” to see exactly how much you will have paid by the end of the loan term.

Avoiding Common Financial Pitfalls

Before signing any agreement, it is vital to read the fine print. Many people fall into the trap of only looking at the monthly payment amount. However, the total cost of the loan is determined by the APR and the length of the term. A small monthly payment over a long period can end up costing significantly more in the long run.

For example, a $2,000 loan with a $100 monthly payment sounds manageable, but if the term is 36 months, you will have paid back $3,600—meaning you paid $1,600 in interest alone. Another mistake is failing to compare options. Even if you are in a rush, taking ten minutes to check a second or third lender can save hundreds of dollars.

Always ensure you are not paying hidden fees or unnecessary service charges that could eat into your holiday budget. Watch out for “origination fees”—charges taken directly from the loan amount before you even receive the cash—as these can significantly decrease the actual amount of money you receive.

Finally, consider your repayment plan. The goal of a holiday loan should be to bridge a temporary gap, not to create a long-term debt burden. Plan to pay the loan back as quickly as possible once the holiday season ends and your normal income stream resumes. By being diligent now, you can enjoy the festivities without the lingering shadow of financial stress in January.

Call Now Button