Categories
Uncategorized

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Holiday loans for bad credit

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season often brings a whirlwind of expenses that can catch anyone off guard. Between unexpected gifts, last-minute travel tickets, and seasonal hosting costs like grocery surges and decor, the financial squeeze can feel overwhelming. For those facing the holidays with less-than-perfect credit, finding a reliable way to bridge the gap is essential for a stress-free December.

Rather than relying on high-interest payday loans that can lead to a cycle of debt, many are turning to specialized lenders that prioritize speed and accessibility. When selecting a lender, the priority shifts from finding the lowest APR to finding speed and accessibility.

A lender that offers quick funding can be a lifesaver when a last-minute purchase is needed, such as a sudden car repair required to get home for the holidays or an unexpected catering bill for a family gathering. It is vital to look for transparency regarding fees and how the application process might impact your current credit standing.

Understanding the difference between a “hard pull”—which can temporarily lower your score—and a “soft pull”—which is essentially harmless—is the first step in making an informed decision.

  1. JetzLoan
  2. Addition Fi
  3. OppLoans
  4. World Finance
  5. Sound Credit Union
  6. OneMain Financial

How These Holiday Lenders Were Evaluated

The ranking process focused on speed, accessibility, and the ability to secure funds despite a challenging credit history. Each option was assessed based on how quickly money hits a bank account and whether the application process involves a hard credit pull. This is a crucial distinction for anyone looking to shop around without damaging their score.

We analyzed the “time-to-cash” metric, which measures the elapsed time from the moment you click “apply” to the moment the funds are available for spending in your checking account. Accessibility was also a key pillar. Lenders were evaluated on their ability to serve individuals who might be turned down by traditional banks.

Traditional banking institutions often rely heavily on FICO scores and long-term credit history, which can be a barrier for those with recent setbacks. Our evaluation looked for providers that offer clear terms, minimal hidden fees, and a straightforward path from the initial application to receiving the necessary cash for seasonal needs.

We specifically prioritized lenders that provide a “pre-qualification” step, allowing you to see potential terms before committing to a formal application.

Lender Name Max Loan Amount Funding Speed Credit Impact Terms/Rates
JetzLoan $50,000 As little as 24 hours No hard credit pull See site
Addition Fi See site See site See site See site
OppLoans See site Same-day funding available No FICO score impact See site
World Finance See site See site See site
Sound Credit Union See site See site See site
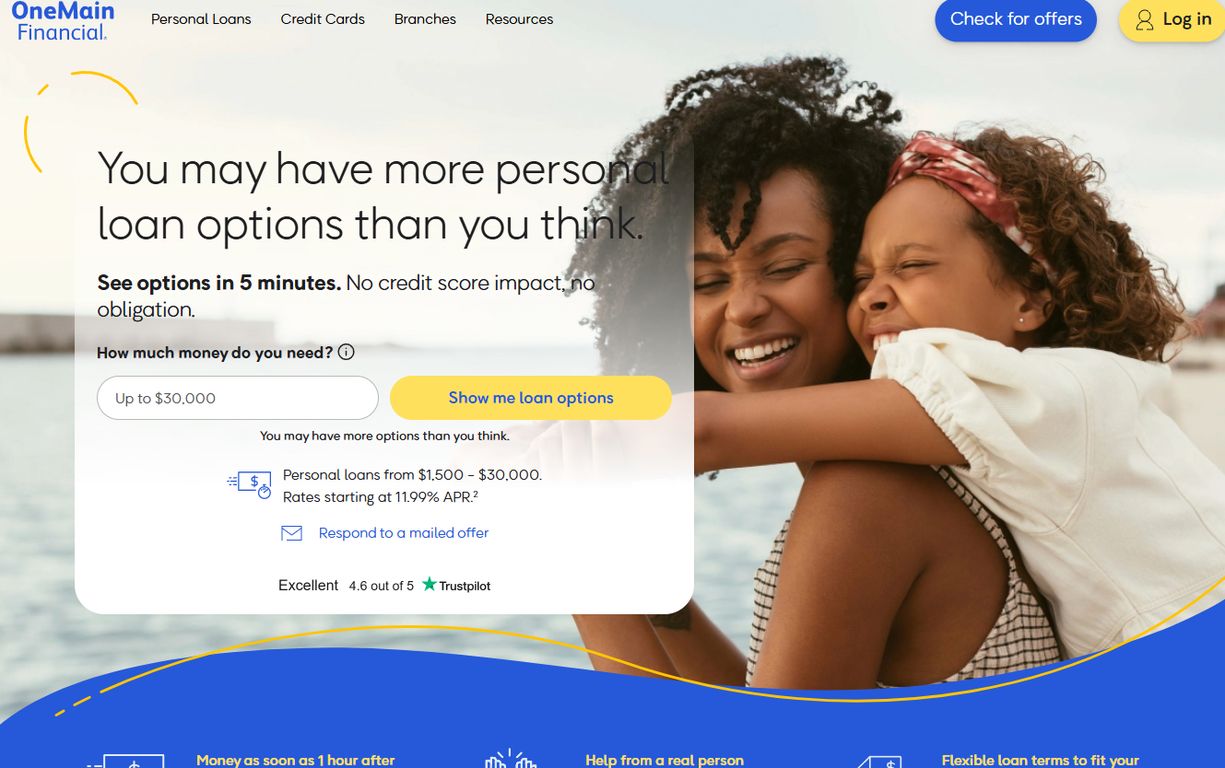
OneMain Financial $30,000 As soon as 1 hour No credit score impact Starting at 11.99% APR

Top Rated Lenders for Seasonal Funding

1. JetzLoan
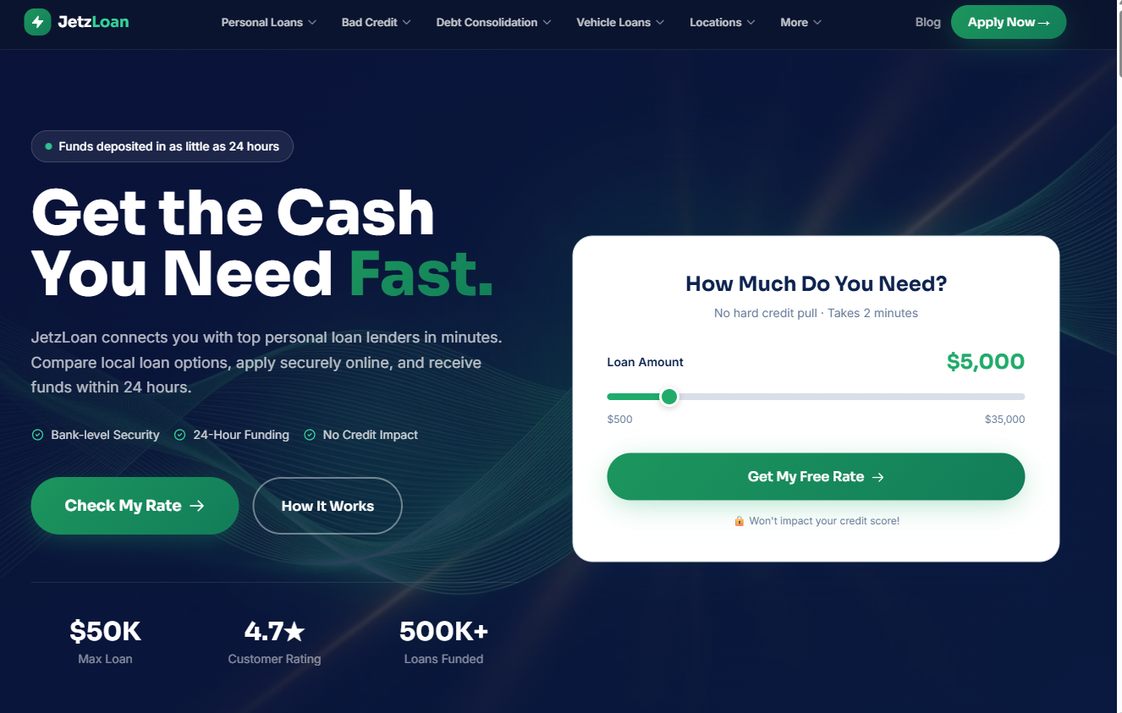
JetzLoan – jetzloan.com

JetzLoan connects borrowers with top personal loan lenders in just a few minutes. It is an ideal solution for those who need a significant amount of cash, with loan limits reaching up to $50,000. The process is designed to be incredibly fast and transparent, removing the bureaucratic red tape often found in big-box banking. (jetzloan.com)

This option is perfect for individuals who need flexibility without the fear of a credit score dip. Because there is no hard credit pull during the initial check, you can explore your options freely. This “soft inquiry” approach allows you to gauge your eligibility and potential interest rates without the risk of a score decrease.

Funds can be deposited into your account in as little as 24 hours. This makes it suitable for those facing a tight deadline, such as a holiday travel booking that is about to expire.
Pros:

  • High maximum loan amount of $50,000
  • Fast 24-hour funding
  • No hard credit pull during the rate check
Cons:
  • Connecting with lenders takes a few minutes of application time

2. Addition Fi
Addition Fi – additionfi.com

Addition Financial operates as a full-service credit union, offering a wide variety of banking products. While they provide traditional loans, their focus is on building a long-term relationship with members. They offer competitive rates designed to help people borrow smarter and save more over time.

Unlike some predatory lenders, credit unions are member-owned. This means their primary goal is to serve their community rather than maximize shareholder profits. This is a great choice for those who want more than just a quick loan. They provide checking, savings, and various investment options.

It is a more stable, community-oriented approach for anyone looking to manage their finances more holistically during the holidays. If you are planning to make a large purchase, such as a used vehicle for holiday travel, their specialized loan products might offer better terms than a general personal loan.

Pros:

  • Diverse range of banking and investment services
  • Competitive rates on various products
  • Member referral incentives available
Cons:
  • May require membership to access full benefits

3. OppLoans
OppLoans – opploans.com

OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their platform works with bank partners to provide personal loans that consider more than just a FICO number. They look at a broader range of financial data, which is helpful for individuals who may have a high income but a low credit score due to past student loans or medical debt.

Speed is their specialty, with same-day funding available if you are approved. The application is quick and easy, often providing decisions within minutes. This makes them a streamlined option for those facing an immediate cash crunch during the holiday season, such as a sudden need for emergency home repairs before guests arrive.

Pros:

  • Same-day funding available
  • Decisions often made in minutes
  • Does not affect FICO score when applying
Cons:
  • Approval is subject to bank partner criteria

4. World Finance
World Finance – worldfinance.com

World Finance provides a broad spectrum of financial services, ranging from retail banking to specialized asset management. They offer a sophisticated approach to finance that covers everything from insurance to complex investment strategies and corporate governance. Their infrastructure is designed to handle a wide variety of financial needs, making them a versatile option for a diverse client base.

This entity is suited for individuals or businesses needing specialized financial structures rather than a simple quick cash injection. Their scope is much wider than a standard personal lender, offering deep expertise in various global economic sectors.

If your holiday needs involve more complex financial planning or business-related seasonal inventory financing, their expertise may be relevant.
Pros:

  • Extensive range of financial services
  • Expertise in multiple banking sectors
Cons:
  • May be more complex than a simple holiday loan provider

5. Sound Credit Union
Sound Credit Union – soundcu.org

Sound Credit Union serves its members with a comprehensive suite of loan products. They offer everything from personal and student loans to specialized financing for RVs, boats, and motorcycles. Their focus is on providing a variety of paths to meet different financial goals, ensuring that members have options whether they are looking for a small personal loan or a large asset-backed loan.

For those who need a specific type of loan, such as an auto or home loan, they offer a structured environment. They provide a range of services including mobile and online banking, making it easy to manage your money on the go. This is particularly useful during the holidays when you might be traveling and need to check your balance or transfer funds instantly via your smartphone.

Pros:

  • Wide variety of specialized loan types
  • Convenient mobile and online banking
  • Comprehensive service list from checking to retirement
Cons:
  • May require specific membership criteria

6. OneMain Financial
OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those needing quick access to personal loans between $1,500 and $30,000. They pride themselves on offering more options than most people expect. You can often see your potential options in just five minutes without any obligation, which is ideal if you are comparing multiple lenders at once.

If you need money immediately, they offer a path to receive funds as soon as one hour after the loan is signed. With fixed monthly payments and terms ranging from 24 to 60 months, they provide a predictable way to handle seasonal expenses. This predictability is vital for budgeting; knowing exactly what you owe each month prevents any surprises when you are trying to save for January expenses.

Pros:

  • Extremely fast funding (as soon as 1 hour)
  • Fixed monthly payments for budget stability
  • Large network of 1,300 branches for personal help
Cons:
  • Interest rates can vary based on creditworthiness

Step-by-Step: How to Apply for Seasonal Funding

Securing a loan during the busy holiday season requires a methodical approach to ensure you get the best terms without unnecessary delays. Follow these steps to maximize your chances of success:

  1. Assess Your Total Need: Before applying, calculate exactly how much you need. Don’t just guess; look at your gift list, planned grocery budget, and any expected travel costs. Borrowing more than you need can lead to unnecessary interest costs.
  2. Check Your Credit Score: While many lenders offer soft pulls, knowing your score helps you set realistic expectations for the interest rates you might receive.
  3. Gather Documentation: To speed up the process, have your most recent pay stubs, proof of identity (like a driver’s license), and bank account details ready. Digital copies of these documents will significantly reduce application time.
  4. Compare Pre-Qualifications: Use the lenders mentioned above to check your eligibility. Focus on lenders that offer a “no hard credit pull” option to protect your score while you shop around.
  5. Review the Total Cost: Look beyond the monthly payment. Check the “Total Repayment Amount” to see exactly how much you will have paid by the end of the loan term.

Avoiding Common Financial Pitfalls

Before signing any agreement, it is vital to read the fine print. Many people fall into the trap of only looking at the monthly payment amount. However, the total cost of the loan is determined by the APR and the length of the term. A small monthly payment over a long period can end up costing significantly more in the long run.

For example, a $2,000 loan with a $100 monthly payment sounds manageable, but if the term is 36 months, you will have paid back $3,600—meaning you paid $1,600 in interest alone. Another mistake is failing to compare options. Even if you are in a rush, taking ten minutes to check a second or third lender can save hundreds of dollars.

Always ensure you are not paying hidden fees or unnecessary service charges that could eat into your holiday budget. Watch out for “origination fees”—charges taken directly from the loan amount before you even receive the cash—as these can significantly decrease the actual amount of money you receive.

Finally, consider your repayment plan. The goal of a holiday loan should be to bridge a temporary gap, not to create a long-term debt burden. Plan to pay the loan back as quickly as possible once the holiday season ends and your normal income stream resumes. By being diligent now, you can enjoy the festivities without the lingering shadow of financial stress in January.
Categories
Uncategorized

The 6 Best Lenders for Roof Financing in 2026

Roof financing

The 6 Best Lenders for Roof Financing in 2026

Last updated: 2026-10-16

A leaking roof is more than a nuisance. It is a direct threat to your home’s foundation. When rain starts dripping through the ceiling, homeowners often scramble to find the liquid cash needed for immediate repairs. Water infiltration leads to mold, electrical hazards, and compromised beams. This can turn a simple shingle replacement into a catastrophic renovation project.

Financing helps bridge the gap between a sudden emergency and long-term stability. It allows you to secure materials and professional labor before the damage spreads. Choosing a lender depends on your credit health and how fast you need the money. Some people need funds by tomorrow morning for a contractor’s deposit. Others want the lowest interest rate to keep total costs down.

A homeowner with a 780 credit score might access premium, low-interest unsecured loans. Meanwhile, someone with a 620 score might prioritize approval speed over the lowest APR. Every financial situation requires a different strategy to get the job done right.

  1. JetzLoan
  2. LightStream
  3. United Finance
  4. Allegiance Credit Union
  5. Roadrunner Financial
  6. Avant

How These Financing Options Were Evaluated

We matched specific lender profiles with the common needs of homeowners facing roofing dilemmas. Speed of funding was a primary metric. Water damage does not wait for a slow approval process. We gave significant weight to lenders offering rapid, digital-first applications. We looked at how quickly a user moves from “application submitted” to “funds in bank.”

Accessibility for various credit tiers was another major factor. Roofing is often an unplanned expense. Many applicants might not have a perfect credit score due to recent life changes. We prioritized lenders that offer transparent terms without impacting credit scores during the initial inquiry. This allows consumers to window shop for the best rates using soft credit pulls.
We also examined the flexibility of loan terms. A roof replacement can cost $6,000 for a small repair or $25,000 for a full installation. Lenders offering tiered loan amounts and adjustable repayment periods are more valuable for the diverse range of roofing needs encountered by modern homeowners.

Lender Name Max Loan Amount Funding Speed Credit Requirements Other Notable Details
JetzLoan $50,000 As little as 24 hours No hard credit pull to check rate 4.7★ Customer Rating
LightStream See site Next day funding possible Excellent credit required for lowest rate 9.99%–24.94% APR with AutoPay
United Finance $20,000 See site See site See site Established 1922
Allegiance Credit Union See site See site See site Serves central Oklahoma
Roadrunner Financial See site Real-time decision All credit scores welcome Specializes in powersports/vehicles
Avant See site See site See site Offers credit cards and loans

Ranking the Top Lenders

1. JetzLoan

JetzLoan – jetzloan.com

When the clouds turn gray and the drips start hitting the floor, time is the ultimate enemy. JetzLoan connects homeowners with top personal loan lenders in minutes. This is built for those who value speed above almost everything else. If you are dealing with an active leak during a storm, you cannot wait for a loan officer to call you back on Monday.
The platform is incredibly user-friendly. You can fill out a simple form in under two minutes. This efficiency is a lifesaver for those who need to secure a roof before a storm hits. It provides a way to get cash quickly without the usual headache of traditional banking bureaucracy. The digital interface works great on mobile, so you can start the process from your phone in your driveway.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull to check your initial rate.
  • High customer satisfaction with a 4.7-star rating.

Cons:

  • Maximum loan amount is capped at $50,000.

2. LightStream

LightStream – lightstream.com

LightStream is a heavyweight in the lending space, especially for those with a stellar credit history. They offer an uncomplicated approach to lending. It is a breath of fresh air when you are already stressed about home maintenance. They specialize in high-value, low-interest personal loans for almost any purpose, including a full roof overhaul.

Their rates are quite competitive if you use AutoPay. This makes them a premier choice for the financially savvy homeowner. This lender is ideal for someone who has been diligent about their finances and wants to leverage good credit for a low fixed rate. It is a smooth, digital experience that can get funds into your account as quickly as the next day.

Pros:

  • Low fixed rates starting from 9.99% APR.
  • AutoPay discounts are available to lower costs.
  • Very fast approval and funding process.

Cons:

  • Requires excellent credit to access the best rates.
  • Rates are higher if you do not use AutoPay.

3. United Finance

United Finance – unitedfinance.com

Stability is the name of the game with United Finance. Having been in business since 1922, they bring a level of institutional trust that is hard to find in the modern fintech era. While many newer apps pop up and disappear, United Finance has weathered nearly a century of economic shifts. This provides security for those worried about the longevity of their lender.

They offer a straightforward approach to personal loans for home repairs. If you want a lender that understands the value of a long-standing reputation, this is a strong contender. They offer personal loans up to $20,000. This is a solid choice for medium-sized roofing projects or minor repairs, such as replacing a chimney flashing or a few damaged shingles.

Pros:

  • Decades of experience and proven reliability.
  • Simple and accessible online application process.
  • Personal loans available for big and small needs.

Cons:

  • Loan amounts are capped at a lower $20,000 limit.

4. Allegiance Credit Union

Allegiance Credit Union – allegiancecu.com

Credit unions often feel like a community. Allegiance Credit Union is no exception. They focus heavily on the individual story, whether you are saving for a first home or rebuilding after a setback. This mission-driven approach makes the borrowing process feel much more personal than dealing with a faceless national conglomerate.

Serving central Oklahoma since 1963, they are a great option for members who prefer a local institution over a massive national bank. Their products are designed to help you borrow smarter and build a stronger financial future. Because they are member-owned, their interests are often more closely aligned with yours than a traditional profit-driven bank.

Pros:

  • Strong focus on member financial well-being.
  • Community-oriented service model.
  • Provides various tools to help meet life goals.

Cons:

  • Membership is likely restricted to specific geographic areas.

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a bit of a wildcard in the roofing space. Their primary expertise lies in powersports financing. However, their streamlined, rapid decision-making process is highly efficient. They are built for speed and ease of use, making them a unique option for non-traditional borrowing needs.

The beauty of their system is the lack of commitment during the prequalification phase. You can see what you qualify for without any impact on your credit score. This is a massive relief when you are just trying to gauge your options. It is particularly useful if you are comparing several different loan offers simultaneously to see which fits your monthly budget.

Pros:

  • Real-time decisions with no credit score impact.
  • All credit scores are welcome.
  • Personalized loan offers that remain valid for 30 days.

Cons:

  • Specializes in vehicle/powersports, which may limit roofing-specific terms.

6. Avant

Avant – avant.com

Avant is a versatile player that caters to various financial life stages. Whether you need a personal loan for home improvement or a credit card to cover a sudden emergency, they offer a suite of solutions. Their digital platform handles the complexities of modern life, providing a clear interface for managing your debt.

They focus on flexibility. No two financial journeys are exactly the same. This makes them a good fallback option for those who need a specific tool for a specific problem, like an unexpected roofing bill. If you aren’t sure whether a single large loan or a credit card with a lower limit is better, Avant’s diverse lineup offers that choice.

Pros:

  • Wide range of products including credit cards and loans.
  • Flexible choices designed to meet diverse needs.
  • Friendly support and user-friendly digital tools.

Cons:

  • May not offer the specialized rates of a dedicated home improvement lender.

Comparing Loan Types for Roofing Projects

When deciding how to fund your roof, you must understand the distinction between different types of debt. Most homeowners choose between a personal loan, a home equity line of credit (HELOC), or a specialized home improvement loan. Each has a different impact on your financial profile and your home’s equity.

Loan Type Speed of Funding Impact on Equity Best For…
Personal Loan Fast (1-3 days) None (Unsecured) Emergency repairs and smaller projects.
HELOC Slow (Weeks) High (Secured) Large, planned renovations with high budgets.
Home Equity Loan Slow (Weeks) High (Secured) Fixed-rate financing for massive structural work.

For an emergency leak, a personal loan is almost always the superior option because of the speed of funding. Waiting three weeks for a HELOC appraisal while rain is actively pouring into your living room is not a viable strategy. However, if you are replacing the entire roof on a large estate, a home equity product may offer much lower interest rates over a longer period.

Navigating the Financing Landscape

Before signing anything, you must shop around. A single interest rate difference might seem small on paper—perhaps only 0.5%—but over a five-year loan, it can represent thousands of dollars in extra interest. Always compare the total cost of the loan, including any hidden fees or origination costs that might be rolled into the principal balance.

One common mistake is rushing into the first offer because you are in a panic. While speed is essential, a desperate decision can lead to predatory terms or high APRs. Take a moment to check if the lender offers a “no hard credit pull” option. This “soft pull” allows you to compare JetzLoan against LightStream without any penalty to your creditworthiness.

Finally, ensure the loan term aligns with your monthly budget. A longer term, like 60 or 72 months, will lower your monthly payment. This is great for immediate cash flow and keeping overhead low. However, it will significantly increase the total interest you pay over the life of the loan. Aim for the shortest term you can comfortably afford to minimize the “cost of money.”

Categories
Uncategorized

Top 4 Dental Financing Options Ranked for 2026

Dental financing

Top 4 Dental Financing Options Ranked for 2026

Last updated: 2026-10-16

Walking into a dentist’s office only to receive a price tag that feels like a punch to the gut is a common nightmare. Most people find themselves staring at a bill for implants or crowns, wondering if they will ever see their bank account balance rise again. Whether it is an emergency root canal necessitated by a sudden infection or a planned cosmetic procedure like veneers that promises a total transformation, the upfront cost can be staggering. Finding a way to bridge that gap without breaking the bank is essential for maintaining both your physical health and your financial stability.

Choosing the right way to pay for your smile isn’t just about the monthly payment. It involves looking at interest rates, how a lender treats your credit score, and how quickly you can get the green light. A high interest rate might make the monthly installment seem manageable, but over a 24-month period, you could end up paying thousands more than the actual cost of the dental work. Conversely, a lender that requires an impeccable credit score might leave you in pain while you wait weeks for an approval. This ranking looks at the most prominent players in the market to help you decide which path leads to a healthy smile.

  1. CareCredit
  2. Cherry
  3. FastLendGo
  4. iCare

How These Dental Payment Solutions Were Evaluated

The selection process focused on the specific needs of patients facing unexpected oral health costs. We looked at whether a lender provides quick decisions, which is vital when a toothache won’t quit. Speed often matters just as much as the actual cost of the loan when you are in pain. If you are sitting in a waiting room with a throbbing molar, you don’t want to be told you have to wait three business days for a manual underwriting process to finish. You need a solution that works in real-time.

We also weighed the accessibility of these options for individuals with varying credit profiles. Some patients have pristine scores and can qualify for the lowest possible APRs, while others are just trying to keep their heads above water and may have a history of late payments or high credit utilization. A good financing partner should offer a way forward, regardless of whether your credit history is a polished gem or a bit of a mess. We evaluated lenders based on three primary pillars: speed of approval, ease of application, and the breadth of credit eligibility. We also considered the “hidden” costs, such as origination fees or penalties for early repayment, which can turn a simple payment plan into a long-term debt trap.

Lender Name Primary Use Case Speed of Decision Credit Requirement Loan Amounts
CareCredit Health & Wellness Instant Subject to Approval See site
Cherry Flexible Payment Plans Fast Broad Eligibility See site
FastLendGo Personal Loans Quick All Credit Tiers $500 – $5,000+
iCare No-Nonsense Financing Instant No Credit Check See site

Understanding the Cost of Delaying Care

It is tempting to push a dental bill to the “next month” pile, but in dentistry, procrastination is often the most expensive financial decision you can make. Oral health issues are rarely static; they are progressive. A small cavity that costs $200 to fix today can evolve into a cracked tooth requiring a $1,500 crown in six months, or an even more expensive $2,500 root canal and buildup if the infection reaches the nerve.

When comparing financing options, it is helpful to view the cost of the loan against the cost of the untreated condition. If a lender offers a 0% interest plan for six months, the “cost” of the money is effectively zero, making it a highly efficient way to manage cash flow. However, if you choose a high-interest personal loan to avoid a waiting period, you must calculate if the interest paid is less than the projected increase in the cost of the dental procedure if it worsens. In many cases, the interest on a loan is a small price to pay to prevent a surgical emergency later.

Ranking the Best Lenders for Your Dental Care

1. CareCredit

CareCredit – carecredit.com

CareCredit operates as a specialized health and wellness credit card designed for medical and dental needs. It is a heavy hitter in the industry, accepted at over 285,000 locations. This makes it a very convenient choice if your dentist is already part of their vast network of providers. Because it is a dedicated credit line, it doesn’t clutter your primary personal credit card utilization, which can help keep your credit score stable if managed correctly.

The application process is designed to be painless, offering instant credit decisions so you aren’t left waiting. It is an ideal solution for those who want a dedicated line of credit specifically for health-related expenses and want to pay over time. Many providers offer “deferred interest” promotions—for example, 6, 12, or 24 months of 0% interest. This is a powerful tool, but it comes with a significant caveat: if you fail to pay the full balance by the end of the promotional period, you are often backdated and charged all the interest that would have accrued from day one. You must be disciplined to make this work.

Pros:

  • Extremely wide acceptance at dental offices nationwide.
  • Instant decisions mean you can start treatment quickly.
  • Prequalification does not impact your credit score.

Cons:

  • Subject to credit approval and standard card terms.

2. Cherry

Cherry – trycherry.com

Cherry has carved out a niche by offering more modern, patient-friendly payment plans. They are known for having broader eligibility criteria, which is a breath of fresh air for those who might be nervous about traditional bank loans. It feels less like a rigid contract and more like a helpful tool. Instead of a revolving credit card, Cherry often functions more like a structured installment loan, where you know exactly how much you owe and when each payment is due.

This option is perfect for patients who want a straightforward payment structure without the heavy lifting of traditional credit cards. It aims to make ownership of your dental care feel immediate and much less intimidating for the average person. Because Cherry integrates directly with many dental practice management softwares, the checkout process at the dentist’s office is often as simple as a few clicks on a tablet, allowing you to walk out with your treatment scheduled and your financing settled in minutes.

Pros:

  • Broad eligibility criteria for a wider range of people.
  • Provides a flexible alternative to standard credit cards.
  • Streamlined process for quick payment plan setups.

Cons:

  • May not offer the same high limits as traditional credit lines.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, including dental work. They cater to a wide spectrum of borrowers, from those with great credit to those struggling with bad credit. This makes them a go-to for people who need a personal loan specifically for dental care where the dentist’s in-house financing might be too restrictive or unavailable. Unlike a credit card, which you use at the point of sale, a personal loan from FastLendGo is often deposited directly into your bank account.

If you need a lump sum of cash to cover a large procedure, this is a strong contender. They offer various loan sizes, starting from small amounts like $500 up to $5,000 or more, making them quite flexible for different treatment scales. This is particularly useful if you are paying a dentist who does not participate in any third-party financing programs. Having the cash in hand allows you to negotiate a “cash discount” with some providers, which can sometimes offset the interest cost of the loan itself.

Pros:

  • Accepts various credit levels, including bad credit.
  • Offers specific loan amounts for different needs.
  • Quick access to cash for immediate dental repairs.

Cons:

  • The interest rates can vary significantly based on credit.

4. iCare

iCare – icarefinance.com

iCare takes a very different approach with its patented, no-nonsense program. The standout feature here is the ability to offer 0% interest financing with no credit check and instant approval. This is a game-changer for patients who cannot afford to wait or undergo a rigorous credit investigation. For many, the idea of a “credit check” is a source of immense anxiety, fearing that a rejection will further damage their score or that a high-interest rate will follow them for years.

This option is tailor-made for the patient who needs a customized, hassle-free way to pay for care. It removes the “fear factor” often associated with financing, allowing the focus to remain on oral health rather than financial anxiety. It is an ideal bridge for those who might be in a temporary cash crunch but have a steady income that supports monthly installments. By decoupling the financing from traditional credit scoring, iCare opens doors for many who would otherwise be forced to delay essential care.

Pros:

  • Offers 0% interest options.
  • No credit check required for instant approval.
  • Highly customizable financing structures.

Cons:

  • Availability may depend on the specific provider’s setup.

Comparing Financing Types: Credit Cards vs. Personal Loans vs. Installment Plans

To choose the best path, you must understand the structural differences between these financial tools. Not all “debt” is created equal, and the way you repay it determines your long-term financial health.

Feature Credit Card (e.g., CareCredit) Personal Loan (e.g., FastLendGo) Installment Plan (e.g., Cherry)
Structure Revolving (can be used repeatedly) Lump Sum (one-time use) Fixed Term (fixed monthly payments)
Interest Type Often promotional 0% (then high APR) Fixed APR throughout term Typically fixed or low-cost
Impact on Credit Affects utilization and payment history Affects debt-to-income ratio Minimal impact if structured as a service
Best For Long-term, high-value procedures When you need cash in your own bank account Predictable, monthly budgeting

Avoiding Common Financial Pitfalls

Before you sign on the dotted line, always look at the fine print regarding interest. It is easy to get caught up in the excitement of a “no credit check” offer, but you must understand if the total cost of the procedure increases significantly due to fees or deferred interest. For instance, if a plan offers 0% interest for 12 months but charges a 5% “origination fee” upfront, your actual cost of borrowing is higher than it appears. Always ask your dentist how they handle these specific providers and if there are any administrative fees associated with setting up the plan.

Another mistake is ignoring the impact on your budget. A monthly payment might look small on paper—say, $75 a month—but when stacked with a car payment, a phone bill, and rising grocery costs, it can become a mountain that is difficult to climb. A “payment shock” occurs when a patient realizes they have committed to several different financing plans at once. Make sure the payment schedule fits your lifestyle, not just your immediate need for a new tooth. Always aim to pay off your dental financing as quickly as possible; even if you have a 0% interest plan, paying it off early provides peace of mind and frees up your monthly cash flow for other life necessities.

Categories
Uncategorized

The Best Options for Bad Credit Loans in Texas: A 2026 Ranking

Bad credit loans texas

The Best Options for Bad Credit Loans in Texas: A 2026 Ranking

Last updated: 2026-10-17

Trying to manage money in Texas can feel like driving through a sudden thunderstorm without wipers. When your credit score isn’t where you want it, finding a lender feels less like a stroll and more like a marathon. You need more than a quick cash injection; you need a lifeline that won’t pull you under.

Whether you are facing a sudden transmission failure in Houston or an unexpected medical bill in Dallas, the stakes are high. The temptation to grab the first offer is strong when you are under pressure. You want a solution that actually helps instead of adding to the chaos.

This list is for Texans facing unexpected hurdles, from auto repairs to medical bills. Choosing the right lender requires looking past the glossy advertisements to find actual stability. We focused on finding institutions that prioritize accessibility and transparency, ensuring you can rebuild your footing without falling into a debt trap.

In a state where the cost of living fluctuates wildly between major cities and rural counties, knowing your options is your best defense. Understanding the fine print helps you avoid predatory lending practices that target those in a pinch. Knowledge is the best way to keep your finances on track.

  1. Texas Bay Credit Union
  2. Solarity Credit Union
  3. TexasLoansToday
  4. Wisetack

How Texas Lenders Were Evaluated

Finding the right fit for bad credit loans in Texas isn’t just about finding the fastest money, though speed certainly helps. It is a balance between how easy it is to get approved and the long-term cost of that debt. A lender that says “yes” too easily might be charging interest rates that will keep you broke for years.

We analyzed the fine print of various lending models. We compared the Annual Percentage Rate (APR) against the speed of disbursement to see which lenders offer the best value for immediate needs versus long-term health. Speed is great, but it shouldn’t come at the cost of your future income.

The comparison focused on several key areas: the ease of the application, the speed of funding, and the flexibility of terms. We looked for lenders that serve a wide range of Texas cities and those that offer specialized products like credit builder options. Every entry was vetted to ensure they provide genuine service to those with less-than-perfect credit histories.

We specifically prioritized lenders that offer “soft pulls” for pre-qualification. This allows Texans to shop around without the penalty of a hard inquiry on their credit report. When your score is already fragile, avoiding unnecessary hits to your report is a crucial factor in maintaining stability.

Lender Name Loan Amounts Funding Speed Credit Impact Best For
Texas Bay Credit Union Up to $2,000 (Starter) See site See site Building Credit
Solarity Credit Union See site See site See site Business & Personal
TexasLoansToday $500 – $35,000 24 Hours No Hard Pull Fast Funding
Wisetack See site Under a minute See site Home Services

Top Ranked Texas Lenders for 2026

1. Texas Bay Credit Union

Texas Bay Credit Union – texasbaycu.org

Texas Bay Credit Union acts as a steady hand for those just starting their financial journey. They offer specialized starter loans designed specifically for individuals with little to no credit history. These loans are capped at $2,000, which makes them an excellent entry point for anyone looking to prove their reliability to future lenders.

Unlike traditional big-box banks that might automatically reject a profile with a thin credit file, Texas Bay looks at the broader picture of your financial stability. They understand that everyone starts somewhere, and they provide the tools to help you move forward from that starting point.

Beyond basic credit building, they provide options like auto financing to help you stay on the road. Their products are built to be flexible, ensuring that your budget isn’t stretched to a breaking point. For example, their auto financing programs are tailored to help you secure reliable transportation without the predatory interest rates often found in “buy here, pay here” lots.

Pros:

  • Starter loans specifically for building credit.
  • Flexible auto financing options.
  • Established credit union stability.

Cons:

  • Starter loan amounts are limited to $2,000.

2. Solarity Credit Union

Solarity Credit Union – solaritycu.org

Solarity Credit Union approaches banking with a focus on brightness and simplicity. They cater to a wide demographic, from individuals needing personal support to businesses looking for commercial real estate or lines of credit. Their model is built around providing guidance alongside modern digital tools.

They aim to fill the gap between the convenience of a fintech app and the security of a traditional financial institution. If you are looking to manage both personal and business needs, Solarity offers a comprehensive suite of services. They emphasize a “brighter” banking experience, which translates to knowledgeable employees who actually take the time to listen.

Whether you are a small business owner in Austin trying to expand your inventory or a resident in San Antonio looking to consolidate high-interest debt, their consultative approach helps you map out a path forward. They do more than just hand you a check; they help you understand the implications of your financial choices.

Pros:

  • Wide variety of business and personal products.
  • Emphasis on expert guidance and support.
  • Modern digital banking tools.

Cons:

  • May require more traditional documentation than online-only lenders.

3. TexasLoansToday

TexasLoansToday – texasloanstoday.com

When time is of the essence, TexasLoansToday steps up to the plate. They serve over 1,200 Texas cities and towns, making them a true statewide powerhouse. Their primary advantage is speed, often providing a decision on your application within a single day through a very streamlined process.

In emergencies—such as a sudden plumbing crisis or an urgent repair needed to keep a vehicle on the road for work—this speed can be the difference between stability and catastrophe. They are built for those who cannot afford to wait weeks for a bank’s committee to meet.

This lender is particularly friendly to those worried about their credit score. They offer a “no hard credit pull” option, meaning you can check your rates and see what you qualify for without any damage to your score. This is a critical feature for those attempting to rebuild their credit, as every hard inquiry can shave points off an already delicate score.

Pros:

  • Extremely fast 24-hour funding.
  • No hard credit pull during the initial check.
  • Wide coverage across Texas.

Cons:

  • High interest rate potential for some users.

4. Wisetack

Wisetack – wisetack.com

Wisetack operates a bit differently than a traditional bank, focusing on the intersection of consumers and home service businesses. If you need a repair done on your house—such as HVAC work, roofing, or electrical repairs—this is the way to go. It allows you to see your financing options in under a minute through a simple text or invoice link.

This removes the need to fill out lengthy, intimidating paperwork at a bank branch. The beauty of this system is the transparency. Both the customer and the service provider know exactly what the costs are upfront, which eliminates that awkward “sticker shock” at the end of a job.

This integration creates a closed-loop system where the money goes directly to the service provider, ensuring the job is completed and the consumer is protected. It is highly rated by users who prefer a frictionless, digital-first experience that prioritizes clarity over complexity.

Pros:

  • Instant visibility of financing options via text/link.
  • High customer satisfaction ratings.
  • Seamless integration for home service businesses.

Cons:

  • Limited to financing specific home service transactions.

Understanding the True Cost of Borrowing

Before signing any agreement, it is vital to perform a mathematical autopsy on the loan terms. Many borrowers focus solely on the monthly payment, but this is a dangerous metric. A low monthly payment often indicates a longer loan term, which can result in you paying double or triple the original amount by the time it is satisfied.

To avoid this, you must look at the Total Cost of Loan. To calculate the real impact on your wallet, use this simple step-by-step method:

  1. Identify the APR: Do not just look at the interest rate; look at the Annual Percentage Rate, which includes fees.
  2. Calculate Total Interest: Multiply the monthly payment by the total number of months in the term, then subtract the original principal.
  3. Factor in Fees: Add any origination fees, processing fees, or administrative charges to that total.
  4. Compare: Compare this “all-in” number against other offers to see which lender is actually cheaper over the life of the loan.

For example, a $2,000 loan with a 5% interest rate over 12 months is vastly different from a $2,000 loan with a 25% interest rate over 36 months, even if the monthly payments seem manageable in both scenarios. The latter will cost you thousands more in interest, effectively turning a small repair into a long-term financial burden.

Strategies for Rebuilding Credit While Managing Debt

Taking out a loan to cover a current need should not be a permanent setback. In fact, if managed correctly, it can be the catalyst for improving your financial profile. The goal is to use the liquidity to solve an immediate problem while simultaneously implementing habits that prevent the need for high-interest loans in the future.

Consider the following tactical steps to ensure your borrowing experience leads to growth:

  • Prioritize Credit Builder Products: If your goal is to fix your score, a specialized credit builder product like those offered by Texas Bay Credit Union is often a much smarter move than a standard installment loan. These products are designed to report positive payment history to the bureaus without requiring a large upfront sum.
  • Set Up Autopay: Late payments are one of the fastest ways to destroy a recovering credit score. Even a single 30-day late payment can drop your score significantly. Setting up automatic withdrawals ensures you never miss a due date, even during busy or stressful months.
  • Avoid “Credit Stacking”: It is tempting to take out multiple small loans to cover different expenses. This is a recipe for a debt spiral. Instead, look for a single consolidation option if possible, or prioritize the highest-interest debt first using the “Avalanche Method.”
  • Review Your Statements Monthly: Don’t wait for a collection agency to call. Regularly checking your bank statements and credit reports allows you to catch errors or unauthorized charges before they escalate into serious legal or financial issues.

Making the Right Choice for Your Wallet

The biggest mistake people make when seeking bad credit loans in Texas is rushing into the first offer they see. It is tempting to grab the quickest cash, but a high-interest loan can quickly become a mountain of debt. Always ask about the total cost of the loan, including all fees and the full APR. A lender who is transparent about these costs is a much safer bet than one who hides them in the fine print of a digital application.

You should also consider whether you need a general personal loan or a specific product like a credit builder loan. If your goal is to fix your score, a specialized credit builder product is often a much smarter move than a standard installment loan. Take a breath, compare the numbers, and choose the path that leads to growth, not a cycle of debt. Your financial future in Texas depends on the decisions you make during these critical moments of need.

Categories
Uncategorized

Top 5 Lenders for Motorcycle Loans for Bad Credit in 2026

Motor cycle loans for bad credit

Top 5 Lenders for Motorcycle Loans for Bad Credit in 2026

Last updated: 2026-10-16

Trying to score a new bike when your credit score is in the gutter feels like hitting a brick wall. Many riders assume a bruised credit history means they are destined to ride a beat-up old machine forever. Perhaps you have a history of late payments or a high debt-to-income ratio. Maybe a recent bankruptcy is still haunting your reports. Regardless of the cause, being denied a loan when you have your heart set on a specific machine is incredibly discouraging.

The reality is that the lending world has shifted. The era of “one size fits all” banking is fading. It has been replaced by a fragmented market where specialized lenders find value in segments that traditional big-box banks often overlook. This list focuses on finding lenders who see the person behind the numbers. They offer pathways to ownership even when your financial past has been a bit bumpy or unpredictable. Whether you want a high-performance street bike or a reliable commuter, there is a financial lane carved out for you.

  1. Roadrunner Financial
  2. FastLendGo
  3. OneMain Financial
  4. SCU Credit Union
  5. Sound Credit Union

How We Evaluated These Lending Options

Evaluating lenders for bad credit requires a different lens than traditional prime lending. When you have a score above 740, lenders compete for your business with the lowest possible rates. When you are working with a score in the 500s or low 600s, the criteria shift. You stop asking “how much can they offer me?” and start asking “will they offer me anything at all?” We looked beyond just the lowest interest rates to see who actually provides accessibility for those with less-than-perfect scores.

It isn’t just about saying “yes.” We looked at how they say it, how they handle your data, and whether their terms are predatory or merely challenging. We prioritized speed and the ability to prequalify without hurting your score. We also looked at the breadth of vehicle types covered. A lender that only works with brand-new motorcycles isn’t helpful if you are hunting for a vintage cafe racer or a used dirt bike.

We also scrutinized the “hidden” costs. Items like origination fees or prepayment penalties can make a “cheap” monthly payment much more expensive in the long run. This is especially true if you plan to pay the loan off early once your credit improves. You don’t want to find out later that you’re locked into a high-cost contract just because the initial monthly payment looked low on the sticker.

Lender Name Loan Amounts Terms Funding Speed Credit Requirements
Roadrunner Financial See site See site Quick Process All credit welcome
FastLendGo $500 – $5,000+ See site Quick access Bad/Fair Credit
OneMain Financial $1,500 – $30,000 24 – 60 months As soon as 1 hour See site
SCU Credit Union See site 60-month options See site New & Used vehicles
Sound Credit Union See site See site See site RV, Boat & Motorcycle

1. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial acts as a bridge between riders and dealerships. They specialize in powersports financing, covering everything from ATVs and side-by-sides to dirtbikes and snowmobiles. It is a heavy hitter for anyone looking to secure a ride at a local dealership without the usual headache. Instead of you running from bank to bank, Roadrunner works with a network of dealers to streamline the approval process.

The standout feature here is the ability to check your rate in about two minutes. This process uses a “soft pull” mechanism. It doesn’t touch your credit score, so you can shop around without the fear of dropping your points further. This is a critical tool for anyone trying to gauge their purchasing power. For example, if you find a used Yamaha XT250 at a dealership, you can quickly see if Roadrunner can facilitate that specific purchase before you even drive to the lot.

Because they focus on the dealership model, they are highly integrated into the sales process. When you sit down with a salesperson, the financing is often already moving in the background. This makes the “buying experience” feel less like a negotiation and more like a transaction. This is especially helpful for those who find the high-pressure environment of a dealership intimidating.

Pros:

  • Prequalify with no impact on credit score
  • Covers a massive range of powersports including golf carts
  • Real-time decisions to save time at the dealership

Cons:

  • Primarily focuses on dealership-based financing rather than direct personal loans

2. FastLendGo

FastLendGo – fastlendgo.com

If you find yourself in a pinch and need cash to secure a deal, FastLendGo offers a direct path. They specialize in personal loans that cater specifically to those with bad or fair credit. Unlike traditional auto loans that are tied to a specific VIN, a personal loan from FastLendGo gives you the cash to buy a bike from a private seller on Craigslist or Facebook Marketplace. This is a common scenario for riders looking for deals on older, high-mileage bikes.

This lender is particularly useful for people who need quick access to cash for various needs, including motorcycle loans. They offer different tiers, from $500 up to $5,000 and beyond. This makes them a flexible partner for many different financial situations. For instance, if you need $2,000 to buy a used Honda Rebel from a private party, a traditional bank might refuse the loan because there is no collateral. FastLendGo’s unsecured personal loan model is designed for exactly this type of flexibility.

Pros:

  • Specialized options for bad and fair credit
  • Quickly compare local personal loan options
  • Flexible loan amounts starting at $500

Cons:

  • Interest rates for bad credit can be significantly higher than prime loans

3. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a massive player in the personal loan space, offering a structured approach to borrowing. They provide loans ranging from $1,500 up to $30,000, which covers the majority of used motorcycle price points. If you are looking to upgrade from a 250cc commuter to a mid-sized cruiser, OneMain’s loan ceiling is likely sufficient to cover the gap.

The speed of funding is impressive. You could have money available as soon as one hour after signing. This rapid turnaround is ideal for riders who have found a “unicorn” bike—a rare model that won’t be available by tomorrow. With fixed monthly payments and terms between 24 and 60 months, it provides a predictable way to manage your debt while you enjoy your new ride. You won’t have to worry about your payment amount changing halfway through the loan term.

Pros:

  • Very fast funding, potentially within one hour
  • Large loan amounts up to $30,000
  • Fixed monthly payments for easier budgeting

Cons:

  • Requires visiting a branch or interacting with their specific system

4. SCU Credit Union

SCU Credit Union – scucu.org

Credit unions often hold the secret sauce for better rates. Unlike commercial banks that answer to shareholders, credit unions are member-owned non-profits. SCU Credit Union offers financing for both new and used motorcycles, including popular brands like Honda and Harley-Davidson. They are a great option for those looking to consolidate existing debt while getting a bike. If you have several high-interest credit card balances, using a SCU loan to roll those into one lower-interest payment can be a powerful way to clean up your balance sheet.

Because they are a credit union, the focus is often on the member’s long-term financial health. They tend to look at the “whole person.” They might consider your steady employment history or your community ties rather than just a single numerical score. Whether you are looking for a 60-month term or looking to build your savings simultaneously, they offer a suite of services that go beyond just the loan itself. They are an excellent choice for the rider who plans on staying with the same institution for years to come.

Pros:

  • Financing available for new and used motorcycles
  • Options to consolidate debt
  • Expertise in various vehicle types

Cons:

  • Membership requirements may apply to certain credit union benefits

5. Sound Credit Union

Sound Credit Union – soundcu.org

Sound Credit Union serves a wide variety of needs, including specialized loans for RVs, boats, and motorcycles. They are a comprehensive institution that looks at your total financial picture. This makes them a “lifestyle” lender for those who don’t just want a motorcycle, but perhaps a trailer to haul it or a boat for the weekend.

For the rider who wants a relationship with their bank, Sound is a strong contender. They offer specialized motorcycle loans that can help you get on the road while maintaining a banking relationship for your future financial needs. This relationship can be invaluable. Once you have established a history of on-time payments with Sound, your next loan—perhaps for a car or a home down payment—may be much easier to secure.

Pros:

  • Specialized motorcycle and powersports loan focus
  • Full suite of banking services available
  • Comprehensive financial support

Cons:

  • Might require more paperwork compared to instant-decision online lenders

Preparation: Improving Your Chances Before You Apply

While the lenders listed above are willing to work with less-than-perfect credit, your chances of securing a lower interest rate increase significantly if you take proactive steps before hitting the “apply” button. Think of this as “pre-flighting” your financial situation.

First, pull your credit report from all three major bureaus (Equifax, Experian, and TransUnion) to ensure there are no errors. A single incorrect late payment reported by a previous landlord or a utility company can tank your score by 50 points. If you find errors, dispute them immediately. A “pending dispute” status can sometimes be taken into account by manual underwriters.

Second, prepare a “financial dossier.” When dealing with lenders like Sound or SCU Credit Union, being able to immediately provide two months of pay stubs, proof of residence, and a clear summary of your monthly expenses can set you apart. It demonstrates that you are a responsible, organized individual. This builds trust, which is the most important currency in the world of subprime lending.

Third, consider a co-signer. If you have a family member with strong credit who is willing to back you, this can be a game-changer. A co-signer essentially tells the lender, “If this rider fails to pay, I will.” This significantly lowers the lender’s risk. It can often move you from a “denied” status to an “approved” status with a much more manageable interest rate.

Navigating the Road Ahead

Before you sign on the dotted line, remember that a loan is a commitment. When dealing with bad credit, the interest rate is often the price you pay for the privilege of immediate ownership. It is vital to look at the total cost of the loan, not just the monthly payment. A $200 monthly payment might seem manageable, but if that payment is spread over 72 months at 18% interest, you will end up paying nearly double the actual value of the motorcycle.

Always ask for the “Truth in Lending” disclosure. This is a standardized document that lenders are legally required to provide. It breaks down the total amount you will pay over the life of the loan, including all interest and fees. If a lender is hesitant to provide this or tries to hide the total cost in fine print, walk away immediately.

Avoid the mistake of rushing into a deal just because a dealer is pushing you to sign. High-pressure sales tactics are common in powersports, especially when they know your credit is a weak point. They may try to offer you a “no money down” deal that looks attractive, but it carries an astronomical interest rate that keeps you in debt for years. Take a moment to compare the offers you received during the prequalification stage. A little bit of patience now can save you thousands of dollars in interest. Your goal shouldn’t just be to get a bike; it should be to get a bike and remain financially free while riding it.

Categories
Uncategorized

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Car repair loans for bad credit

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Last updated: 2026-10-16

Walking into a mechanic’s shop only to find out your transmission needs a complete overhaul is a gut punch. When the repair bill looks more like a mortgage payment, the stress can feel overwhelming. For many drivers, a sudden mechanical failure is a crisis that demands immediate cash to keep life moving.

A failed alternator might cost $400, but a transmission swap or an engine replacement can easily soar into the $3,000 to $5,000 range. This creates an immediate liquidity gap that most monthly budgets cannot absorb without planning. It is a sudden, sharp financial blow that catches most people off guard.

Finding a lender that accepts less-than-perfect credit scores is the primary goal for most people in this situation. When your credit score has been impacted by medical bills, student loans, or previous missed payments, traditional banking institutions often become inaccessible. You find yourself staring at a locked door when you need a way out.

This ranking focuses on speed, accessibility, and the reality of borrowing when your credit history isn’t your strongest asset. It is about getting back on the road without sinking further into a financial hole. We looked at how these lenders actually function when you are in a pinch.

  1. Manhattan Bank
  2. FastLendGo
  3. Addition Fi
  4. Minute Loan Center
  5. CreditNinja

How We Evaluated These Repair Financing Options

The selection process prioritized lenders that cater specifically to those facing unexpected automotive expenses. We looked for providers that offer quick turnaround times, which is critical when you need your vehicle for work or family obligations. Speed is often the difference between getting to a job and losing a paycheck.

If you are a delivery driver or a commuter with a long distance to travel, a three-day waiting period for funds might mean losing several shifts of income. This effectively increases the “true cost” of the loan. You aren’t just paying interest; you are paying for the time you spent without a car.

We also examined the breadth of loan products offered by each entity. A lender that provides various amounts, from small emergency sums to larger amounts, offers more flexibility for different repair scenarios. A simple brake pad replacement might only require a $300 quick loan.

Conversely, a blown head gasket might require $2,500. We looked for lenders that don’t force you into a massive loan if you only need a small fix, and those that can scale up for major structural repairs. The following comparison highlights the key features available for each provider based on their current service offerings.

Lender Name Loan Amounts Funding Speed Credit Requirements
Manhattan Bank See site See site See site
FastLendGo $500 – $5,000 See site Bad/Fair Credit
Addition Fi Up to $5,000 See site See site
Minute Loan Center See site Same-day Fair Credit
CreditNinja See site Same day* Bad Credit

The Best Lenders for Automotive Repairs

1. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank operates as a traditional banking institution with the security of FDIC insurance. This provides a level of peace of mind that many specialized online lenders simply cannot match. For those who prefer working with a formal bank structure, this is a solid option for various personal loan needs.

Because they are a full-service bank, they offer a more structured approach to borrowing. While this might mean a slightly more thorough vetting process—often involving a review of your debt-to-income ratio and employment history—the stability of an FDIC-insured institution is a massive advantage for long-term financial health.

When applying with a traditional bank, you are typically looking for a “Personal Loan,” which is unsecured. This means you don’t have to put your vehicle up as collateral, which is a significant relief if you are already struggling with car-related expenses. You can keep your title in your hand.

However, because they prioritize stability, they may require a more established banking history or a steady stream of documented income via pay stubs or W-2s. They want to see that your income is as reliable as their vaults.

Pros:
  • FDIC-insured security
  • Established banking reputation
  • Offers personal loans for many occasions
Cons:
  • May have more rigorous application requirements than quick-cash lenders

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo specializes in being a partner for those who might struggle with traditional bank requirements. They offer a wide range of specialized products, including specific options for auto repair loans and even motorcycle loans. This makes them a versatile choice for various mechanical emergencies.

Instead of trying to fit a square peg into a round hole with a general-purpose loan, FastLendGo‘s specialized products are tailored to the reality of automotive ownership. They understand that a car isn’t just a luxury; it is often a tool for survival.

With loan amounts ranging from $500 up to $5,000, they cater to both small fixes and larger, more significant engine repairs. This range is particularly useful for tiered repair needs. You can address the immediate crisis without over-borrowing.

For instance, if your mechanic says, “You need a new fuel pump now, but you can wait six months on the suspension,” FastLendGo allows you to borrow exactly what is needed for the immediate crisis. Their focus on high-speed access makes them a strong contender for anyone in a time-sensitive situation.

Pros:
  • Specific auto repair loan options
  • Flexible loan amounts from $500 to $5,000
  • Designed for bad and fair credit
Cons:
  • Limited to specific states

3. Addition Fi

Addition Fi – additionfi.com

Addition Financial Credit Union offers a membership-based approach to personal banking. For those looking to build a long-term relationship with a financial institution, this is a standout choice. Credit unions are member-owned cooperatives, which often means they operate with a different philosophy than for-profit banks.

Their primary goal is to serve their members, which can translate to more personalized service and competitive terms. It feels less like a cold transaction and more like a community resource. They aren’t just looking at numbers on a screen; they are looking at people.

They offer competitive rates and a variety of loan products. While they are a broader credit union, their ability to help members “borrow smarter” makes them a reliable option for those who want to manage their debt responsibly while fixing their vehicle.

Because credit unions often have slightly more flexible underwriting criteria than large national banks, they may be more willing to look at the “why” behind a low credit score—such as a past medical emergency—rather than just the score itself. They see the human story behind the data.

Pros:
  • Credit union membership benefits
  • Competitive rates for members
  • Diverse range of financial products
Cons:
  • Requires membership to access full benefits

4. Minute Loan Center

Minute Loan Center – minuteloancenter.com

When the car is stuck in the shop and the clock is ticking, Minute Loan Center offers a rapid response. They focus heavily on the speed of the application and the immediacy of the funds. Their model is built for people who need cash to be deposited as soon as the same business day.

This is a vital feature for those living paycheck to paycheck, where a three-day delay in funds could mean a late fee on rent or a missed utility payment. In these moments, every hour feels like a lifetime. They aim to cut that waiting time down to almost nothing.

The platform is designed to be straightforward, aiming to help users step into financial freedom through quick approvals. The digital-first approach means you can often complete the entire process from your smartphone while waiting in the mechanic’s lobby.

This is ideal for the driver who cannot afford to miss a day of work because their vehicle is sidelined and they need to authorize the repair immediately to get it back on the road. They prioritize getting you back to work, which keeps your income flowing.

Pros:
  • Same-day deposit potential
  • Fast approval process
  • User-friendly online application
Cons:
  • Approval is dependent on fair credit status

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja acts as a bridge for those who find themselves unable to get approved by traditional lenders. Their system is designed to match users with loan options that fit their specific credit profile. It is a way to stop guessing and start knowing.

Rather than you spending hours applying to ten different lenders only to get ten rejections, CreditNinja uses a matching algorithm to point you toward the lenders most likely to approve your specific situation. It is a streamlined way to find a solution when other doors have closed.

The process is quick and simple, focusing on providing a fast decision. If you are in a pinch and need to know where you stand without a long, drawn-out waiting period, this is an efficient way to explore your options.

It acts as a powerful reconnaissance tool for anyone who is unsure of their eligibility in a high-pressure environment. It helps you narrow your search so you aren’t wasting energy on lenders that will simply say no.

Pros:
  • Same-day decision potential
  • Quick and simple online application
  • Targets those with bad credit
Cons:
  • Does not guarantee approval

Understanding the Total Cost of Borrowing

When you are in an emergency, it is easy to focus solely on the monthly payment, but this can be a dangerous trap. To truly understand your financial obligation, you must look at the Annual Percentage Rate (APR). This includes both the interest rate and any mandatory fees.

A loan with a “low” monthly payment might actually be more expensive over the long term if the interest rate is significantly higher than a standard bank loan. Don’t let a small number hide a large debt. Look at the grand total you will pay back by the end of the term.

Consider these three factors when reviewing a loan offer:

  • The Repayment Term: A 24-month loan will have much lower monthly payments than a 12-month loan, but you will pay significantly more in total interest over that extended period.
  • Origination Fees: Some lenders deduct a fee from the loan amount before you even receive it. If you need exactly $1,200 for a repair but the lender charges a $100 origination fee, you will only receive $1,100, leaving you short at the mechanic.
  • Prepayment Penalties: If you receive a bonus at work or a tax refund and want to pay off the car loan early to save on interest, some lenders charge a fee for doing so. Always check if “prepayment is without penalty.”

Smart Steps to Prepare for Your Loan Application

Securing a loan under pressure is difficult, but being prepared can increase your chances of approval and better terms. Even if you are applying for a high-speed loan, having your documentation ready can prevent delays that could leave you stranded without transport.

Follow these steps to streamline the process:

  1. Gather Documents: Have your most recent pay stubs, a government-issued ID, and your bank account details (for direct deposit) ready. If you are self-employed, have your last two years of tax returns on hand.
  2. Get a Written Estimate: Do not guess the amount you need. Ask your mechanic for a detailed, written estimate that includes parts and labor. Borrowing too little leads to more debt later; borrowing too much leads to unnecessary interest.
  3. Check Your Own Credit: While you may have bad credit, knowing your score helps you understand which lenders (like CreditNinja or FastLendGo) are your most viable targets.
  4. Verify Your Income: Lenders want to see that you have the ability to repay. Even if your credit is poor, a stable, documented income is your strongest asset during the underwriting process.

Navigating your borrowing options requires a balance of urgency and caution. Before signing any paperwork, it is vital to look at the total cost of the loan. Interest rates can vary wildly between a traditional bank and a specialized lender. Always ask for the total amount you will be paying back over the life of the loan, not just the monthly payment.

Another common pitfall is rushing into a high-interest loan just to solve an immediate problem. While speed is important, an expensive loan today can become a heavy burden tomorrow. Compare your options carefully and ensure the repayment schedule fits comfortably within your monthly budget.

If a monthly payment would mean you can’t afford groceries or gas, the loan is too large or the term is too long. You shouldn’t have to choose between fixing your car and feeding your family. Take a breath and look at the math one more time.

Finally, read the fine print regarding any fees. Some lenders charge origination fees or prepayment penalties that can catch you off guard. Taking ten minutes to read the terms can save you hundreds of dollars in the long run, ensuring your car repair doesn’t lead to a financial disaster. Your goal is to get back on the road, not to remain stuck in a cycle of high-interest debt.

Categories
Uncategorized

Top 5 Lenders for Same Day Personal Loans in 2026

Same day personal loans

Top 5 Lenders for Same Day Personal Loans in 2026

Last updated: 2026-10-16

Life rarely waits for a convenient time to throw a curveball. Whether it is an unexpected car repair that leaves you stranded, an urgent medical bill, or a leaking roof that needs immediate attention, finding quick cash can feel like chasing a ghost in a crowded room. In these high-stress moments, the mental bandwidth required to handle complex financial systems often vanishes first.

This is why many people turn to same-day personal loans to bridge the gap between a sudden crisis and their next paycheck. Choosing a lender is about more than just who moves the fastest. If you prioritize speed above all else, you might find yourself trapped in a high-interest cycle that takes years to escape.

It is about finding a balance between speed, cost, and the long-term impact on your financial reputation. This ranking looks at the most reliable options currently available to help you handle these high-pressure moments without making a mess of your future. We have analyzed the top players in the market for 2026.

  1. JetzLoan
  2. Avant
  3. SoFi
  4. Discover
  5. CreditNinja

How the Top Lenders Were Evaluated

The selection process focused heavily on how fast money hits your account and how easy the application feels. Nobody wants to spend hours filling out paperwork or waiting on hold with a representative only to wait a week for a decision. We looked for lenders that offer digital-first experiences and rapid deposit timelines using modern banking technology.

Beyond speed, we looked at accessibility and transparency. We prioritized lenders that provide clear information regarding credit impacts and loan amounts. It is vital to know if a hard credit pull is required before you start clicking buttons, as this can affect your ability to secure a mortgage or an auto loan later.

A “soft pull” allows you to shop around for the best interest rate without a penalty. This is a critical distinction for anyone trying to maintain a healthy credit profile while seeking emergency funds. We also evaluated the friction within the application journey, such as whether a lender uses automated systems like Plaid to verify income instantly or requires manual pay stubs.

The goal was to identify lenders that respect your time as much as your money. We wanted to see who makes the process painless and who leaves you scrambling for documentation. The following table summarizes our findings across the top five candidates.

Lender Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Avant $2,000 – $35,000 Fast decision See site
SoFi See site See site See site
Discover $2,500 – $40,000 As early as next business day No impact to credit score for pre-approval
CreditNinja See site As soon as the same day See site

Ranking of Best Lenders

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with various top lenders in a matter of minutes. Rather than being a single bank, it functions as a marketplace. This is a significant advantage because it saves you the time of visiting ten different websites to see who will give you the best rate. Instead, you enter your data once, and the platform does the heavy lifting.

The process is remarkably streamlined, requiring less than two minutes to complete the initial form. This makes it a standout for anyone who needs to move quickly without a heavy administrative burden. For example, if you are at a mechanic’s shop and need to pay for a repair immediately to get your car back, the speed of JetzLoan is designed for that exact scenario.

The platform is built for those who might be nervous about their credit standing. Because they offer a way to check rates without a hard credit pull, you can explore your options without any fear of damaging your score. It is a low-pressure way to find significant funding without the “sticker shock” of seeing a credit score drop before you even know if you qualify.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull required for the initial rate check.
  • High customer rating of 4.7 stars.

Cons:

  • Acts as a marketplace rather than a direct lender.

2. Avant

Avant – avant.com

Avant focuses on providing flexible tools for people who are navigating complex financial journeys. They understand that “one size fits all” rarely works in lending. They offer solutions for various needs, including debt consolidation, emergency expenses, and home improvements. This versatility is helpful for someone trying to solve two problems at once.

You might find yourself needing to pay off a high-interest medical bill and a predatory payday loan in a single lump sum. Their application process is simple, utilizing a three-step method to get you from start to finish. This is ideal for someone who needs a quick decision to handle an unexpected life event.

They aim to provide clarity when you might be facing difficult financial questions. They often provide clear terms upfront so there is no confusion about what your monthly payment will look like. This transparency helps prevent any nasty surprises when the first bill arrives in your inbox.

Pros:

  • Simple, three-step application process.
  • Options for debt consolidation and emergency loans.
  • Flexible solutions for different financial goals.

Cons:

  • Specific eligibility requirements are not always immediately transparent.

3. SoFi

SoFi – sofi.com

SoFi is a massive player in the financial ecosystem, offering everything from banking and checking to investing and mortgages. For those who want a one-stop shop for their entire financial life, this is a powerhouse. They cater to a wide range of needs through digital, automated processes that feel much more like a modern tech app than a traditional bank.

While they are known for more traditional long-term financial products, their digital-first approach allows for much faster movement than old-school banks. They are a great option for borrowers who value a high-tech, integrated experience across all their various money management needs. If you already have a high credit score, SoFi is often the gold standard.

They offer premium rates with zero paperwork for those who qualify. The experience is incredibly fluid, making it easy to manage your finances from your phone. It is a sophisticated option for users who want their lending to match their digital lifestyle.

Pros:

  • Comprehensive financial suite including investing and banking.
  • Highly digital and automated application process.
  • Reputable brand with extensive financial tools.

Cons:

  • May require higher credit standards for the best terms.

4. Discover

Discover – discover.com

Discover brings a sense of traditional stability to the online lending world. They offer a wide range of products, including credit cards and personal loans, with a focus on customer service and security. It is a solid choice for someone who wants a well-established name behind their loan.

You might want to know that if you have a question, there is a massive infrastructure of customer support ready to assist them. The platform is particularly useful for those who want to “check before they commit.” You can see if you are pre-approved for certain products with no impact to your credit score.

This allows for a cautious approach to borrowing in an uncertain economic climate. It is a “try before you buy” model that removes the anxiety of the unknown. If you prefer a lender that feels like a pillar of the industry, Discover is a reliable bet.

Pros:

  • Pre-approval checks do not impact credit scores.
  • Wide range of loan amounts available.
  • Highly rated customer service and security.

Cons:

  • Funding may take until the next business day rather than the same day.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is a go-to option for those who might find traditional banks a bit too stingy. They specialize in helping people who may not qualify for standard loans, offering a path to finding solutions for unexpected life expenses. Their application is designed to be quick and simple, focusing on your specific profile.

The standout feature here is the potential for same-day money. If you are approved and sign for your loan, the funds may be deposited directly into your account as early as the same day. This is a lifesaver when a deadline is looming, such as an eviction notice or a utility shut-off warning.

It is designed for high-stakes situations where every hour counts. While you might pay more for this speed, the ability to resolve a crisis immediately is worth a lot to many people. It is a specialized tool for those in urgent need.

Pros:

  • Potential for same-day funding upon signing.
  • Designed for those who struggle with traditional loan approvals.
  • Quick and easy online application process.

Cons:

  • Interest rates can be higher for those with less ideal credit.

The Step-by-Step Process of Securing a Quick Loan

To ensure you get the best possible outcome, you should approach the application process with a specific workflow. Following these steps can prevent common delays that turn a “same-day” loan into a “three-day” headache.

Step 1: Gather Your Documentation in Advance. Even with automated systems, you will likely need to provide your Social Security Number, your monthly gross income, and your primary banking details. Having a digital copy of your most recent pay stub or a bank statement ready to upload can prevent the application from stalling in the “pending verification” stage.

Step 2: Use a Soft Credit Pull First. Always look for the “check your rate” option. This allows you to see the estimated APR and monthly payment without any risk to your credit score. If the rate is significantly higher than you can afford, you can walk away without any lasting financial damage.

Step 3: Compare the APR, Not Just the Monthly Payment. This is where many borrowers make a mistake. A lender might offer a very low monthly payment, but if that is because they have stretched the loan term out to five years, you will end up paying thousands more in interest. Always look at the total cost of the loan over its entire lifespan.

Step 4: Verify the Funding Method. If you need money today, ensure you have a checking account that supports “Real-Time Payments” or “Instant ACH.” Some lenders can send money instantly, but if your bank only processes transfers overnight, you won’t see that cash until the next business morning regardless of how fast the lender acts.

Avoiding Common Pitfalls When Borrowing

The first mistake many people make is rushing into the first offer they see without looking at the fine print. While speed is the primary goal, the cost of that speed can be high. Always check the total cost of the loan to ensure it is manageable. Specifically, look for “origination fees.”

If you borrow $1,000 but the lender takes a $50 origination fee, you only receive $950, but you still owe interest on the full $1,000. Another trap is forgetting to compare different types of credit. Sometimes, a credit card with a low interest rate might actually be cheaper than a quick personal loan for a small amount of money.

Take a moment to breathe and evaluate your total debt-to-income ratio before signing. If your monthly debt payments already consume a large portion of your income, adding another loan could lead to a cycle of borrowing just to pay off previous debts. Avoid the temptation to borrow more than you absolutely need.

Every dollar borrowed is a dollar that must be repaid with interest. Use these tools as a bridge to get you from one stable point to another, not as a permanent lifestyle adjustment. A loan should be a tool for resolution, not a source of new, ongoing stress.

Categories
Uncategorized

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Christmas loans for bad credit

Top 6 Lenders for Christmas Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season usually brings a bit of magic, but for many families, those festive lights feel a little dim when the mounting expenses start piling up. Between buying gifts for the kids and hosting those obligatory dinners, bank accounts often look pretty thin by mid-December. Trying to bridge that gap without falling into a debt trap is a delicate balancing act.

When you need a quick injection of cash, your biggest worry is usually how a lender will view a less-than-perfect credit history. It isn’t just about finding the money. It is about finding a partner that won’t penalize you for past financial hiccups. Speed, transparency, and the actual cost of borrowing are the three things that matter most for a smart holiday loan.

  1. Wells Fargo
  2. FastLendGo
  3. LendingPoint
  4. VivaLoan
  5. NetCredit
  6. Prosper

How These Holiday Lenders Were Evaluated

Our selection process focused heavily on how fast a borrower can move from an application to having cash in hand. In the middle of the Christmas rush, waiting two weeks for a decision is simply not an option. We looked at how lenders handle diverse credit profiles, including those with bruised scores or high incomes but very limited history.

We also looked at whether loan amounts were flexible and if the terms were clear. It is vital to know exactly how much you can borrow for a specific need, whether it is a $500 emergency or a $10,000 debt consolidation. Only lenders with clear, accessible information regarding their requirements and funding speeds made the final cut for this 2026 roundup.

Lender Name Loan Amounts Funding Speed Credit Requirements
Wells Fargo See site See site See site
FastLendGo $500 – $5,000+ Quick access Bad credit options
LendingPoint $1,000 – $36,500 See site Check rate (no impact)
VivaLoan $100 – $15,000 As soon as tomorrow All credit types
NetCredit Up to $10,000 Same-day funding available See site
Prosper $2,000 – $50,000 Fast access See site

The Definitive 2026 Holiday Loan Rankings

1. Wells Fargo

Wells Fargo – wellsfargo.com

Established financial institutions often provide a sense of stability that newer fintech companies lack. For those looking to manage their finances through traditional banking channels, this option offers a wide range of services, including checking and savings accounts. It is a massive ecosystem built to handle everything from simple daily transactions to complex wealth management needs.

This lender works well for individuals who prefer a traditional banking relationship. You might benefit from additional services like credit cards or home loans here. While it is a powerhouse in the financial sector, the complexity of their product line means you have to look through various offerings to find the specific personal loan that fits your current holiday budget.

Pros:
  • Extensive range of banking services
  • Established and trusted institution
  • Offers specialized accounts like Clear Access Banking
Cons:
  • Complex product ecosystem can be overwhelming

2. FastLendGo

FastLendGo – fastlendgo.com

When the holiday season hits a fever pitch, sometimes you just need a quick fix. This lender specializes in providing various personal financing solutions tailored to different life scenarios. Whether it is for auto repairs or a sudden dental bill, they offer a variety of loan sizes to match the specific emergency at hand. (fastlendgo.com)

They cater to a wide spectrum of borrowers, including those with bad credit or even those seeking first-time loans. It is a versatile option for those tired of the “one size fits all” approach used by big banks. If you are looking for something specific like a $500 or $1,000 loan, this could be a lifeline.

Pros:
  • Specialized loans for specific needs (Auto, Dental, Roof)
  • Covers a wide range of credit scores
  • Simple online application process
Cons:
  • Focuses on niche loan types rather than general banking

3. LendingPoint

LendingPoint – lendingpoint.com

For those who need a more substantial amount of capital to tackle larger holiday debts or home improvements, this lender steps up. They offer significant loan amounts that can help turn financial stress into a manageable plan. It is an excellent choice for anyone looking to consolidate debt or cover an unexpected large expense.

A standout feature here is the ability to check your rate without impacting your credit score. This allows for a “no-risk” exploration of your options before you commit to a formal application. It is a thoughtful approach for people who are cautious about their credit standing during a high-stress season.

Pros:
  • High loan limits up to $36,500
  • Check rates without credit score impact
  • Versatile loan purposes
Cons:
  • May require higher income to secure larger amounts

4. VivaLoan

VivaLoan – vivaloan.com

Speed is the name of the game when the holiday bills start piling up on the kitchen table. This lender is designed for the person who needs cash essentially yesterday. With the ability to get funds as soon as the next business day, they remove the long waiting periods that often plague traditional lending.

They are incredibly inclusive, welcoming all credit types into their application process. The ability to request small amounts, starting as low as $100, makes them highly accessible for minor holiday emergencies. It is a streamlined, five-minute request process that prioritizes your time and immediate needs.

Pros:
  • Extremely fast funding (as soon as tomorrow)
  • Low entry point starting at $100
  • Welcomes all credit types
Cons:
  • Rapid funding often comes with higher interest rates

5. NetCredit

NetCredit – netcredit.com

This lender operates on the philosophy that a person is much more than just a single number in a database. By using advanced algorithms, they look beyond the basic credit score to find a more holistic view of the borrower. This approach is refreshing for those who have been denied by more rigid institutions.

They offer a flexible range of products including personal loans and lines of credit with amounts up to $10,000. The availability of same-day funding is a massive advantage when you are facing a deadline. It is a modern, tech-forward solution for the contemporary borrower.

Pros:
  • Holistic underwriting approach
  • Same-day funding availability
  • Flexible lines of credit available
Cons:
  • Approval is subject to state-specific underwriting partners

6. Prosper

Prosper – prosper.com

Prosper offers a different flavor of lending through its connection to the peer-to-peer model. This can sometimes lead to more competitive options for those who qualify. They provide a variety of tools, including credit cards and investment options, making them a comprehensive platform for those looking to manage long-term financial health.

With loan terms reaching up to six years, it is a solid choice for those who want to spread out their repayments over a longer period. This can lower the monthly impact on your budget, which is vital when you are already juggling many holiday expenses. It is a strategic choice for the long-term planner.

Pros:
  • Longer repayment terms up to 6 years
  • Peer-to-peer model offers variety
  • Highly rated by financial experts
Cons:
  • Minimum loan amounts may be higher than micro-lenders

Avoiding the Holiday Debt Trap

Borrowing money during the holidays can feel like walking a tightrope. It is easy to get swept up in the excitement of the season and forget that every dollar borrowed today is a dollar that must be paid back with interest tomorrow. Before you sign any agreement, take a deep breath and look at the total cost of the loan.

One major mistake is ignoring the fine print regarding late fees and prepayment penalties. You want to be able to pay the loan off early if you find yourself with extra cash in January, but some lenders will penalize you for being responsible. Always ensure that the repayment schedule fits comfortably within your budget for the first three months of the new year.

Another pitfall is the “quick fix” mentality. While a small loan might solve a problem today, it doesn’t address the underlying habit that led to the shortage. Use this holiday cash as a bridge, not a permanent lifestyle adjustment. If you use these funds to create memories rather than just covering old debt, you might find the holiday spirit much more fulfilling.

Categories
Uncategorized

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Emergency loans for bad credit

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Last updated: 2026-10-16

Life has a way of throwing a wrench into even the best-laid plans. A sudden transmission failure leaves you stranded on the highway, an urgent root canal brings an unexpected dental bill, or an HVAC breakdown strikes during a heatwave. In those moments, the need for immediate cash feels overwhelming. When your credit score isn’t exactly a glowing endorsement—maybe due to past medical debt or a period of unemployment—finding a lender feels like searching for a needle in a haystack.

This ranking focuses on speed, accessibility, and transparency for people facing urgent financial hurdles. Finding a lender that accepts less-than-perfect credit is only half the battle. The real challenge is ensuring the terms are manageable and the funds arrive before the crisis peaks. We analyzed several providers to see who stands out in this high-stakes market, looking at everything from digital application friction to the actual speed of capital deployment.

  1. Minute Loan Center
  2. FastLendGo
  3. Avant
  4. World Finance
  5. CreditNinja
  6. Reprise

How These Emergency Lenders Were Evaluated

Selecting the right lender requires looking past the flashy advertisements and marketing slogans. The evaluation process focused on how quickly funds could actually reach a borrower’s bank account after approval. In a true emergency, a three-day waiting period is often the difference between a solved problem and a mounting disaster. If you need to pay a mechanic to get to work on Monday morning, a lender that promises funds by Thursday is effectively useless. Speed is the primary metric of value here.

Beyond speed, the criteria included the ease of the application process and the variety of credit profiles accepted. A lender that requires a mountain of paperwork, physical visits to a branch, or multiple days of manual verification might be too slow for a midnight crisis. We also looked for providers that offer clear pathways for those with bad credit, ensuring no hidden surprises lurk in the fine print, such as predatory prepayment penalties or excessive origination fees that balloon the total cost of borrowing.

Lender Name Speed of Funding Max Loan Amount Credit Requirements
Minute Loan Center Same-Day See site Fair credit accepted
FastLendGo See site $5,000 Bad/Fair/Good
Avant See site See site Less than perfect credit
World Finance See site See site See site
CreditNinja Same-Day (with conditions) See site Bad credit okay
Reprise See site See site See site

Ranked Emergency Loan Providers

1. Minute Loan Center

Minute Loan Center – minuteloancenter.com

When the clock is ticking, Minute Loan Center steps into the ring with a focus on velocity. They specialize in same-day and instant online loans, aiming to get deposits into your account via direct deposit as soon as the business day begins. This makes them a heavy hitter for anyone staring down a deadline, such as a utility shut-off notice or a rent payment that is due by the end of the business day.

They cater specifically to those who might struggle with traditional bank requirements, offering approval even for those with fair credit. Because they have been around for over two decades, they have established a reputation for stability. In an era of fly-by-night fintech startups, having a provider that has weathered multiple economic cycles provides an extra layer of peace of mind. It is a solid choice for quick, digital-first relief when you cannot afford to wait for a manual underwriting process.

Pros:

  • Very fast same-day direct deposit.
  • No hidden fees or credit pulls mentioned.
  • Experienced provider with decades of service.

Cons:

  • Primarily focuses on a specific niche of rapid funding.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, ranging from small $500 loans to larger $5,000 requests. They seem to understand that a car repair requires a different approach than a roof repair. For instance, if you need a small amount to cover a tire replacement, a large installment loan might be overkill. Conversely, if you are facing a major home repair, a tiny microloan won’t cut it.

Their platform is designed to help users compare local options quickly to find that middle ground. (fastlendgo.com) The service is built for those who need to skip the long lines and the endless wait times associated with brick-and-mortar lenders. Whether you have bad credit or are just starting your journey with no credit history, they offer a path forward. It is a flexible option for those who need specific amounts for specific crises, allowing for a tailored approach to borrowing that matches the scale of the emergency at hand.

Pros:

  • Wide range of loan amounts from $500 to $5,000.
  • Covers various needs like auto or dental financing.
  • User-friendly comparison interface.

Cons:

  • The comparison model may lead to multiple offers.

3. Avant

Avant – avant.com

Avant approaches personal finance with a focus on long-term movement rather than just quick fixes. While they handle emergency loans, they also offer tools for debt consolidation and credit cards. This makes them a useful option if your emergency is actually part of a larger financial puzzle. For example, if you are taking a loan to cover a medical bill, Avant might also help you restructure your existing high-interest credit card debt to make your monthly budget more sustainable in the long run.

They are particularly welcoming to those with less than perfect credit, providing a bridge to help you move financially forward. Instead of just handing over cash, they aim to provide solutions that fit into your specific life journey. It is a more holistic approach to borrowing that prioritizes the borrower’s future stability rather than just the immediate transaction. It is ideal for the borrower who wants to solve a current crisis while simultaneously improving their credit standing.

Pros:

  • Supports debt consolidation alongside emergency needs.
  • Tailored solutions for different financial stages.
  • Strong focus on moving a borrower forward.

Cons:

  • May have stricter qualifying criteria than specialized lenders.

4. World Finance

World Finance – worldfinance.com

World Finance is a massive entity in the financial landscape, offering a broad spectrum of banking and investment services. While their focus often leans toward more complex financial structures, they maintain a presence in the retail banking space. This provides a level of professional scale that smaller, online-only lenders lack. For many, there is a psychological comfort in dealing with a large-scale institution rather than an unproven app.

For a borrower in a pinch, they represent a more institutional approach to money management. They are a significant player in the global and retail markets, making them a stable entity in the financial ecosystem. It is a choice for those who want a more traditional, large-scale provider and who may prefer the ability to engage with a provider that has a significant, established footprint in the financial sector.

Pros:

  • Highly established and large-scale institution.
  • Broad range of financial services available.
  • Deep expertise in various banking sectors.

Cons:

  • May feel less specialized for a quick, small-dollar emergency.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is built for the “life happens” moments when traditional banks turn you away. Their application process is designed to be quick and simple, requiring only basic information to see if you qualify. This “soft inquiry” style approach is designed to protect your credit score while you are just testing the waters. It is a streamlined approach for when you simply don’t have time to waste on lengthy applications that might lead to a rejection.

If you are approved, you can potentially see your money deposited the same day. However, there is a catch: you must apply and be approved by 10:30 a.m. on a business day to catch that same-day window. This requires a bit of proactive planning even in an emergency. If you wait until 4:00 p.m. to check your options, you might be looking at a delay that pushes your funds into the next business day, potentially missing your deadline.

Pros:

  • Extremely simple and fast online application.
  • Potentially very fast same-day funding.
  • Designed specifically for those denied by traditional banks.

Cons:

  • Strict morning deadline for same-day funding.

6. Reprise

Reprise – reprise.com

Reprise operates in a slightly different lane, functioning as an enterprise demo creation platform. While they offer sophisticated AI toolset and data injection for agents, they are not a traditional consumer lender for personal emergency cash. Their focus is on helping businesses build powerful product tours for their software or services.

They provide incredible capabilities for capturing screens and creating high-fidelity demos that look like real user sessions. If your “emergency” is actually a business need for high-end presentation tools to close a major sales deal, they are a powerhouse. However, for someone needing cash for a broken water heater or a car repair, they are not the right tool. It is important to ensure you are applying to a lender and not a business software provider.

Pros:

  • Advanced AI toolset for demo creation.
  • High-quality data injection for professional presentations.
  • Excellent for enterprise-level product tours.

Cons:

  • Not a consumer loan provider for personal emergencies.

Essential Steps for Securing an Emergency Loan

Navigating the world of rapid lending requires a strategic approach to ensure you don’t exacerbate your financial situation. Follow these steps to maximize your chances of success and minimize your long-term debt burden:

  1. Audit Your Need: Before applying, calculate the exact amount required. If a repair is estimated at $800, don’t borrow $1,200 just because the lender offers it. The interest on that extra $400 will compound quickly.
  2. Verify the “Total Cost of Credit”: Don’t just look at the monthly payment. Look at the total amount you will have paid back by the end of the term. A low monthly payment often means a much longer term and a significantly higher total cost.
  3. Check for Hidden Fees: Look specifically for “origination fees” (charged upfront), “processing fees,” and most importantly, “late payment fees.” In an emergency, your schedule might be chaotic; you need to know the penalty if a payment is a day late.
  4. Confirm the Funding Method: Not all “same-day” loans are created equal. Some require you to visit a physical location, while others use ACH transfers. For true speed, ensure the lender supports instant direct deposit to your existing checking account.

How to Navigate Emergency Borrowing

The most common mistake is rushing into the first offer you see without checking the details. Even in a panic, take a breath and look at the total cost of the loan. A quick fix can become a long-term headache if the interest rates are not clearly understood before you sign. Interest rates for high-speed, bad-credit loans are naturally higher than traditional personal loans, so the speed comes at a premium price.

Avoid the temptation to borrow more than you absolutely need to resolve the immediate crisis. It is easy to think, “If I’m borrowing, I might as well get extra,” but that extra cash comes with extra cost. Stay disciplined, compare the options, and choose the one that gets you through the storm without drowning you later. Use the emergency as a stepping stone to stability, not as a permanent fixture of your monthly budget.

Categories
Uncategorized

The 7 Best Lenders for a Personal Loan with a Co-signer in 2026

Personal loan with co signer

The 7 Best Lenders for a Personal Loan with a Co-signer in 2026

Last updated: 2026-10-17

Trying to find a lender when your credit score is lagging can feel like driving through a thick fog without headlights. Many people find themselves turning to a parent or a close friend to co-sign, hoping that someone else’s good credit can bridge the gap. This simple favor often makes the difference between a rejected application and getting the cash needed for an urgent car repair or a medical bill.

When you weigh your options, don’t just look at the monthly payment. You have to look at the big picture, including how fast you can get the cash and what the total cost will be over the years. A low monthly payment sounds great until you realize the loan term stretches to 72 months, making the interest payments skyrocket. Similarly, a lender that promises lightning-fast funding might hide massive origination fees that make the loan much more expensive than a traditional bank.

  1. FastLendGo
  2. OneMain Financial
  3. Upgrade
  4. Together Loans
  5. U.S. Bank
  6. MoneyLion
  7. MedLoan Finance

How the Top Lenders Were Evaluated

We spent a significant amount of time looking at current market offerings specifically for people using a co-signer. We wanted to see how lenders handle an application when two different people are involved. It was important to know if the requirements for the co-signer were clear or if the fine print was buried under layers of confusing language.

We investigated whether companies required a joint application or if they allowed a co-signer to simply act as a guarantor. This distinction matters because it changes how much of a risk the second person is taking on. We focused on lenders that made the process straightforward rather than those that added unnecessary paperwork to the pile.

Transparency was our main priority. We looked for companies that provided quick decisions, clear interest rates, and various loan amounts. We also checked the “friction” of the application process. This meant looking at how many documents you need to upload, how easy it is to sign things digitally, and how clearly they explain the Annual Percentage Rate (APR).

Lender Name Loan Amounts Key Terms/Rates Funding Speed Credit Focus
FastLendGo $500 – $5,000+ see site see site Bad to Great Credit
OneMain Financial $1,500 – $30,000 Rates from 11.99% APR As soon as 1 hour Bad Credit Friendly
Upgrade Up to $50,000 Fixed rates available Fast funding Credit Health focus
Together Loans Up to $10,000 24 – 60 months 24-hour approval Trust-based/Bad Credit
U.S. Bank see site see site see site Traditional Banking
MoneyLion Up to $100,000 see site Fast/Expedited available Credit Building focus
MedLoan Finance $500 – $100,000 12-18 Months Interest Free see site Medical Specific

Top-Rated Co-signer Loan Options for 2026

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo helps people who need cash quickly without jumping through a dozen hoops. They work with all sorts of people, from someone needing a $500 emergency fix to someone looking for a larger loan for a major life change. Their rules aren’t as stiff as a bank’s mortgage department, which makes them a good fit for gig workers or anyone with a fluctuating paycheck. (fastlendgo.com)

This lender is a lifesaver if you have a “thin” credit file. If you haven’t used much credit in the past, standard computer algorithms might struggle to understand your reliability. They offer specialized options for high earners and those with poor credit, ensuring almost anyone can find a way to borrow. It is a helpful way to use a co-signer to show the stability that your own history might not prove yet.

Pros:

  • Loan amounts start at $500, making them great for small emergencies.
  • They cover things like dental work or car repairs so you don’t need multiple loans.
  • Flexible options exist for many different credit levels.

Cons:

  • They focus on specific needs, so they might not be the best choice for general debt consolidation.

2. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is perfect for anyone who wants to talk to a real person instead of just an app. With over 1,300 physical branches, they have a presence that most online lenders simply can’t match. If you feel uncomfortable explaining your finances to a computer, sitting down with a loan officer in a real office can make you feel much more secure.

They are built for speed. In some cases, you can have your money just one hour after you sign the paperwork. Their joint loan options are also very easy to use, which helps couples or family members share the responsibility. It takes the guesswork out of having a co-signer on the line.

Pros:

  • You can get funding incredibly fast, sometimes within an hour.
  • A huge branch network means you can get in-person help whenever you need it.
  • Joint loans for $1,500 to $30,000 make the co-signer setup very simple.

Cons:

  • If your credit is low, the interest rates can get quite high, adding up over time.

3. Upgrade

Upgrade – upgrade.com

Upgrade takes a very modern approach, focusing on your financial health over the long haul. They offer everything from credit cards to savings accounts, which makes them a one-stop shop for your wallet. Their website is easy to use, and you can play around with different repayment numbers before you sign anything.

If you are trying to consolidate debt or pay for a big purchase, Upgrade makes the application very smooth. One of the best things they offer is a “soft pull” credit check. This means you can see your estimated monthly payment and APR without hurting your credit score, which is great for shopping around.

Pros:

  • Checking your rate won’t hurt your credit score.
  • You can use the money for almost anything, like home repairs or debt.
  • Some products even include cash back rewards.

Cons:

  • The variety of their products might feel like a bit much if you just want one simple loan.

4. Together Loans

Together Loans – togetherloans.com

Together Loans does things a little differently by looking at trust rather than just a digital score. This is a huge advantage for people who have a great co-signer but a messy credit history. Life happens, and sometimes a single medical bill or a period of unemployment can tank your score, but these lenders look at the human side of the story.

They specialize in loans up to $10,000 and are incredibly fast, often giving approvals within 24 hours. If you need to pay an unexpected bill right away, this is a solid option. Using a co-signer here can help you get much better terms than you would ever find on your own.

Pros:

  • They prioritize trust and personal circumstances over rigid algorithms.
  • The 24-hour approval is perfect for urgent situations.
  • There are no upfront fees, so you get the full amount you asked for.

Cons:

  • The interest rates can be on the higher side, so check the fine print.

5. U.S. Bank

U.S. Bank – usbank.com

If you prefer the feeling of a massive, established institution, U.S. Bank is a very steady choice. They are a great option if you already bank with them. Having an existing account can make the verification process move a lot faster since they already know your cash flow.

They might not be as fast as a new fintech startup, but they have a massive infrastructure behind them. They offer everything from basic checking to wealth management. If you are planning a major life event like a wedding, the stability of a big bank can give you a sense of security.

Pros:

  • They offer high levels of consumer protection and stability.
  • You can get almost every financial service you need in one place.
  • It is very easy to manage if you already use their banking services.

Cons:

  • Their requirements for personal loans can be stricter than smaller, niche lenders.

6. MoneyLion

MoneyLion – moneylion.com

MoneyLion is built for people who do everything on their smartphones. Their app is designed to help you manage daily spending while also working to build your credit. It feels more like a financial assistant than just a place to get a loan.

They offer large loans up to $100,000, which is enough for major changes like starting school. Because they focus so much on credit building, they are a great partner for anyone trying to move away from needing a co-signer. Eventually, the goal is to stand on your own two feet without help.

Pros:

  • They offer very high loan limits for large projects.
  • The app includes many tools to help you learn about credit.
  • The mobile interface is very easy to navigate.

Cons:

  • Some of the faster cash features might come with extra fees.

7. MedLoan Finance

MedLoan Finance – medloanfinance.com

MedLoan Finance is built for one specific thing: medical bills. If you are paying for dental work, LASIK, or a surgery, they provide funding that is designed for the healthcare world. General personal loans don’t always understand the timing of medical costs, but these lenders do.

They offer various loan amounts and even have some interest-free options for certain timeframes. If you have a surgery coming up, using a specialist like this can be much cheaper than taking out a high-interest personal loan from a general lender.

Pros:

  • They are specialists for dental and elective medical procedures.
  • Interest-free options for 12-18 months can save you a lot of money.
  • They handle large medical costs up to $100,000.

Cons:

  • You can’t use this money for anything other than medical expenses.

Understanding the Risks for Co-signers

Being a co-signer is a huge deal. When a friend or family member signs that paper, they aren’t just saying you are a good person. They are legally agreeing to pay the debt if you don’t. If you miss a payment, the lender can go after them for the full amount, including interest and late fees. This can lead to lawsuits or even wage garnishment, and it can absolutely wreck their credit score.

The debt also shows up on their credit report. Even if you pay everything on time, the sheer amount of that loan might make it harder for them to get a mortgage or a car loan later. Lenders see that debt as a potential obligation that might prevent them from paying their own bills. It’s a heavy burden to place on someone you care about.

How to Prepare for a Co-signer Application

If you want the best chance of getting approved, you need to be prepared. This means more than just having your ID ready; you need a rock-solid plan for how you will pay the money back. We suggest taking these steps before you even start the application:

  • Make a Payment Plan: Map out exactly when and how you will pay. Leave some extra room in your budget for months when things might get tight.
  • Check the Co-signer’s Credit: Most lenders want your co-signer to have a score between 670 and 700. If their score is low, you might be wasting your time.
  • Get Your Papers Ready: Lenders will want to see pay stubs, W-2s, and proof of where you live. Having these in a folder can save you days of waiting.
  • Read the Contract Together: Don’t just sign the papers. Sit down with your co-signer and read the part about what happens if you miss a payment.

Before you ask anyone to co-sign, you need to have a very honest conversation. They need to know that they are legally responsible for the money. If you have a falling out or if you lose your job, their credit score will take the hit just as much as yours. Money has a way of straining even the strongest family ties.

Don’t assume a co-signer is just a formality. Lenders treat them as a primary guarantor. If your co-signer’s credit isn’t much better than yours, the lender might still say no or give you a much higher interest rate. In that case, the co-signer isn’t actually helping you save money.

Finally, don’t borrow more than you actually need just because you can. Interest adds up fast, and the total cost can become a massive number over time. Use a co-signer to get a better deal, not just to borrow more money than you can handle.

Call Now Button